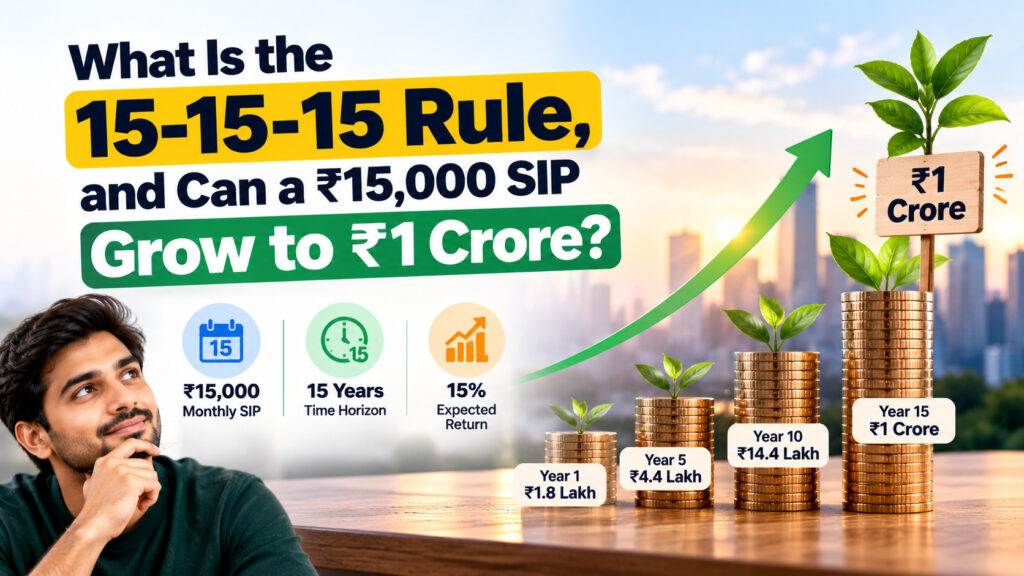
The 15-15-15 Rule is a popular investing illustration: invest ₹15,000 every month for 15 years and assume a 15% annualised return. It can show the power of compounding, but market returns are uncertain and the result is not guaranteed.
Watch the Video: How Does the 15-15-15 Rule Work?
Watch the explanation, then use the calculator below to test different monthly SIPs, time periods and assumed returns.
If you are new to investing, first understand how to start investing in the stock market and how long-term investing differs from short-term trading. The 15-15-15 Rule is a simple way to illustrate how regular investments and compounding may work together over time. It is a learning example—not a promise that a mutual fund will deliver a 15% return.
What Is the 15-15-15 Rule?
The 15-15-15 Rule uses three numbers:
- ₹15,000: the assumed monthly Systematic Investment Plan (SIP).
- 15 years: the assumed investment period.
- 15%: the assumed annualised rate of return, not a guaranteed rate.
With these assumptions, the SIP could grow to around ₹1 crore over 15 years, depending on the calculation method and timing of contributions. The exact estimate varies with the monthly compounding convention, whether contributions are made at the beginning or end of each month, and fees and taxes. Real mutual fund returns do not arrive in a smooth line.
How Much Could a ₹15,000 Monthly SIP Grow In 15 Years?
Here is an illustrative scenario using a monthly SIP of ₹15,000 for 15 years and an assumed 15% annualised return:
| Illustrative item | Amount |
|---|---|
| Monthly SIP | ₹15,000 |
| Investment duration | 15 years (180 monthly instalments) |
| Total amount invested | ₹27,00,000 |
| Illustrative final value | Approximately ₹1 crore, depending on calculation assumptions |
| Potential growth above invested amount | Illustrative only; not guaranteed |
The ₹27 lakh contribution total is simple arithmetic: ₹15,000 × 12 months × 15 years. The final value is a projection based on an assumed rate, not a forecast of what a particular mutual fund will return. Actual values can be lower or higher, and the investment can lose value.
Try the 15-15-15 SIP Calculator
Change the monthly SIP, duration and assumed annual return to see how sensitive the illustration is to your inputs. The calculation below assumes a fixed monthly rate derived from the annual rate, with contributions at the end of each month. It does not include tax, fees or changes in actual market performance.
Illustrative projection only. Returns are not fixed; mutual fund investments are subject to market risk.
What If You Can Invest ₹5,000 or ₹10,000 a Month Instead?
You do not need to begin with ₹15,000 to develop a regular investing habit. The same calculator can model smaller contributions. For example, you can enter ₹5,000 or ₹10,000, choose a time horizon and test several assumed returns. The result will change with every input; no particular corpus is assured.
If you want to understand the difference between regular investing and investing a lump sum, explore our SIP vs lump-sum calculator and SIP vs lump-sum guide. For another view of long-term investing, see our guide to SIPs in mutual funds.
Why Does the 15-15-15 Rule Not Guarantee ₹1 Crore?
The example depends heavily on the assumed 15% annualised return. Mutual fund returns vary with market conditions, portfolio holdings, costs and the period measured. Some years may be positive and others negative. A long-term average does not mean an investor receives the same return each year.
- Returns fluctuate: equity markets can fall, including near the time you need the money.
- Inflation reduces purchasing power: ₹1 crore in 15 years may buy less than ₹1 crore buys today.
- Costs and taxes matter: expense ratios, transaction-related costs and applicable taxes can affect your final amount.
- Goals and risk capacity differ: a 15-year horizon does not automatically make a high-equity investment suitable for everyone.
Use a CAGR calculator to understand annualised growth and a real return calculator to think about inflation-adjusted returns. These tools help with learning; they cannot predict future market performance.
How Should You Plan Before Starting a SIP?
- Protect near-term needs: build an emergency reserve before committing money you may need soon. Read our 3 to 6 Months Emergency Fund Rule guide.
- Set a realistic amount: choose a SIP that fits your income, expenses and existing obligations. Avoid borrowing just to invest.
- Match the investment to the goal: understand the fund’s risk level, investment horizon and asset allocation before choosing a scheme.
- Review periodically: check whether the investment remains aligned with your goal and risk tolerance, rather than chasing whichever fund recently performed best.
For beginner-friendly investor education, visit the SEBI Investor website and the AMFI Investor Corner. Read scheme documents and understand risk before investing.
Quick Quiz: Test Your Understanding of the 15-15-15 Rule
Try five randomly selected questions. Select “New Questions” for another set. The quiz draws from a bank of ten questions, without repeating a question within a single set.
Frequently Asked Questions About the 15-15-15 Rule
Can ₹15,000 a month become ₹1 crore in 15 years?
It may reach around that level under a sufficiently high assumed annualised return, but the result depends on calculation assumptions and actual market performance. It is not guaranteed.
Is a 15% return guaranteed in mutual funds?
No. Mutual funds are market-linked and returns can vary significantly. Do not plan finances on the assumption that a particular return will definitely occur.
Can I use the rule with a ₹5,000 or ₹10,000 SIP?
Yes, you can use the same idea to model a different monthly amount. The projected result will change with the SIP amount, duration and assumed return.
Should I invest in equity funds only because of this rule?
No. Choose investments based on your goals, time horizon, financial situation and ability to accept risk. The rule is an illustration, not a recommendation to buy a particular product.
Where Can You Continue Learning With Stock Charcha?