The Rule of 72 is a quick mental-math shortcut for estimating how long an investment could take to double at a constant annual growth rate. Use it to understand compounding—not to predict or guarantee returns.
Watch the Video: How Does the Rule of 72 Work?
Watch the explanation, then try the calculator below with different assumed annual rates.
If you are learning how to invest, it helps to understand not only how much you invest but also how compounding works over time. The Stock Charcha Knowledge Hub can help you build your financial basics. If you are new to investing, start with our guide to starting stock-market investing and learn how compounding differs from simply saving money. One simple concept to learn is the Rule of 72, a mental shortcut that estimates how many years an investment might need to double if it earns a steady annual rate of return.
What Is the Rule of 72?
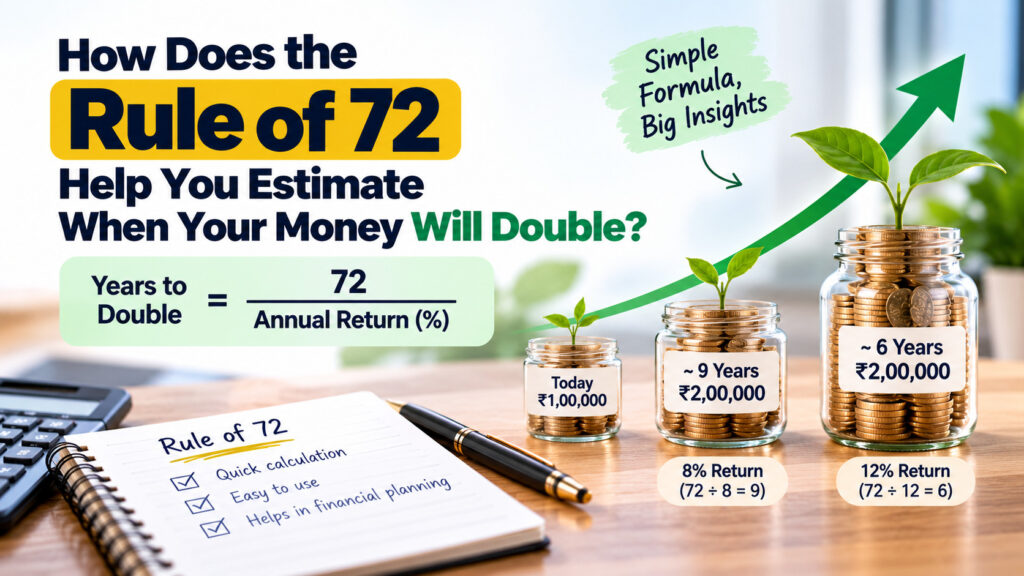
The Rule of 72 is a quick way to estimate the time needed for money to double under a constant annual compound growth rate. Divide 72 by the annual rate of return expressed as a percentage. If the assumed annual return is 8%, for example, 72 ÷ 8 gives an estimate of about 9 years.
The result is an approximation, not an exact forecast. It works best as a quick illustration for positive, steady rates and ordinary compounding assumptions. Real investment returns fluctuate, and taxes, fees, inflation and changes in the amount invested can affect the outcome.
How Do You Calculate the Rule of 72?
There are two common ways to use the Rule of 72. You can estimate how long money might take to double at a given return, or estimate the annual return that would be needed to double money within a chosen number of years.
Example 1: How long could ₹1,00,000 take to double at 8%?
Divide 72 by 8. The estimate is 9 years. Under this simplified assumption, ₹1,00,000 could grow to around ₹2,00,000 in approximately nine years. This is an illustration of compounding, not a promise that a product will deliver 8% every year.
Example 2: What rate could double money in 10 years?
Divide 72 by 10. The estimate is about 7.2% a year. This is a rough implied rate for the shortcut. It does not mean that an investment offering this rate is safe, suitable, or guaranteed.
What Does the Rule of 72 Show at Different Rates?
The table below uses hypothetical annual rates to show how the estimate changes. Actual investment performance can be higher or lower, and negative returns can delay or prevent doubling.
| Assumed annual rate | Rule of 72 calculation | Estimated time to double |
|---|---|---|
| 4% | 72 ÷ 4 | 18 years |
| 6% | 72 ÷ 6 | 12 years |
| 8% | 72 ÷ 8 | 9 years |
| 10% | 72 ÷ 10 | 7.2 years |
| 12% | 72 ÷ 12 | 6 years |
These examples are mathematical scenarios, not current interest-rate quotes or forecasts for fixed deposits, mutual funds, stocks or any other investment. Compare products using their actual terms, risks and costs.
Try the Rule of 72 Calculator
Enter an assumed annual return to estimate the time to double, or enter a target number of years to estimate a rough annual rate. Use the result for learning and comparison only.
This shortcut does not include tax, fees, inflation, irregular contributions or market volatility.
Can You Use the Rule of 72 for Every Investment?
No. The Rule of 72 is a rough teaching tool, not a substitute for evaluating an investment. It is most useful when illustrating a positive, steady compound growth rate. It becomes less reliable at very high or very low rates, and it cannot model changing returns or investment risk.
- Fixed deposits and savings products: check the actual interest rate, compounding frequency, tenure, tax treatment and applicable terms. Do not assume every advertised rate is available for every investor or period.
- Mutual funds and shares: returns are market-linked and can be negative. An assumed 10% return does not mean your investment will earn 10% each year or double on schedule.
- Inflation: doubling the rupee amount is not the same as doubling purchasing power. Rising prices reduce what the money can buy.
- Taxes and fees: costs and taxes may reduce the amount you keep, so the actual time to double your after-cost investment may be longer.
What Are the Benefits and Limitations of the Rule of 72?
| Benefits | Limitations |
|---|---|
| Easy to calculate without a calculator. | Provides an estimate, not an exact answer. |
| Helps explain the effect of compounding. | Assumes a steady rate that real investments may not deliver. |
| Makes it easy to compare hypothetical rates. | Does not measure risk, liquidity, taxes, fees or inflation. |
For decisions involving real money, combine this shortcut with your goals, time horizon, emergency savings and ability to tolerate losses. Review our 3 to 6 Months Emergency Fund Rule guide before investing money you may need soon. You can also explore the CAGR calculator, real return calculator, and XIRR calculator to examine different return measures. For regular investing, see our guide to SIPs in mutual funds and the SIP calculator. These tools are illustrative, not predictions.
Quick Quiz: How Well Do You Understand the Rule of 72?
Answer five randomly selected questions to test the key ideas. Choose “New Questions” for another set. Each set contains five different questions selected from a ten-question bank.
Where Can You Learn More About Investment Risk and Returns?
The Rule of 72 is only a mathematical shortcut. Before choosing an investment, review the product’s risks, costs, and suitability for your goals. The SEBI Investor website provides investor education resources, while the AMFI Investor Corner offers educational material about mutual funds. These sources can help you learn the basics, but neither a formula nor an educational article can guarantee an investment outcome.
Frequently Asked Questions About the Rule of 72
Is the Rule of 72 accurate?
It is a shortcut, not an exact calculation. Its accuracy depends on the rate and compounding assumptions. Use a compound-interest calculator for a more precise estimate under stated assumptions.
Can I use the Rule of 72 for SIP investments?
It is not designed to calculate the doubling time of a SIP with regular contributions. Each contribution is invested for a different length of time, so use a SIP calculator for that scenario.
Does a higher estimated return always mean a better investment?
No. Higher expected returns usually involve different risks, and a high advertised return may come with uncertainty or conditions. Consider risk, liquidity, costs and your goals—not only doubling time. You may also find our mutual funds vs direct stocks comparison useful when learning about different investment routes.
Can the Rule of 72 account for inflation?
Not by itself. You can use an estimated return after inflation to think about real growth, but the result remains an approximation and is not a forecast.
Where Can You Continue Learning With Stock Charcha?