The 100 Minus Age Rule is a simple starting point for understanding how age can influence the balance between equity and debt in a portfolio. It is a thumb rule—not a personalised investment recommendation.
Watch the Video: How Does the 100 Minus Age Rule Work?
Watch this video alongside the guide, then use the calculator below to explore an illustrative equity and debt split.
When you begin investing, one of the biggest decisions is not just which stock or mutual fund to choose, but how much of your overall portfolio should be exposed to different asset classes. The Stock Charcha Knowledge Hub can help you build the basics before making that decision. The 100 Minus Age Rule offers a quick way to start this conversation: subtract your age from 100 to estimate a possible equity allocation, then consider how much could remain in relatively lower-volatility assets such as debt instruments.
What Is the 100 Minus Age Rule?
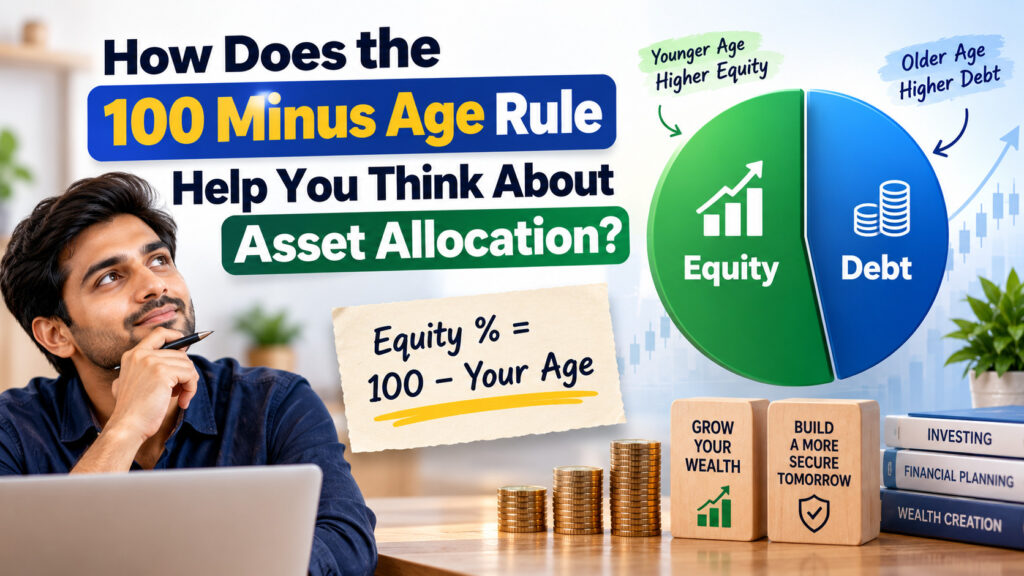
The 100 Minus Age Rule suggests that the percentage of a portfolio invested in equity may be estimated by subtracting your age from 100. The remaining percentage is often assigned to debt or fixed-income investments. For example, a 30-year-old gets a rough equity allocation of 70% (100 − 30) and a 30% allocation to debt. At age 50, the same calculation suggests 50% equity and 50% debt.
The logic behind the 100 Minus Age Rule is that younger investors may have a longer time horizon to ride out market volatility, while investors approaching retirement may want to reduce the impact of a sharp market fall. But age alone cannot tell you how much risk you can afford or should take.
How Does the 100 Minus Age Rule Work With Examples?
Consider the following simplified illustrations. They show what the formula produces—not what every person of that age should invest in equity.
| Investor age | Calculation | Illustrative equity share | Illustrative debt share |
|---|---|---|---|
| 25 | 100 − 25 | 75% | 25% |
| 30 | 100 − 30 | 70% | 30% |
| 40 | 100 − 40 | 60% | 40% |
| 50 | 100 − 50 | 50% | 50% |
| 60 | 100 − 60 | 40% | 60% |
Suppose a 30-year-old has ₹5,00,000 invested for long-term goals. Under the 100 Minus Age Rule, the illustrative split would be ₹3,50,000 in equity and ₹1,50,000 in debt. This is only a mathematical example. It does not account for emergency savings, high-interest debt, near-term goals, job stability, dependants, or the investor’s ability to tolerate losses.
Can You Use This Asset Allocation Calculator?
Enter your age and total investment portfolio below to see the simple split suggested by the 100 Minus Age Rule. Use the result as a discussion starter, not a final portfolio plan.
100 Minus Age Rule Calculator
This tool applies the basic formula only. It does not assess suitability, taxes, risk tolerance or individual financial circumstances.
Why Is the 100 Minus Age Rule Only a Starting Point?
The 100 Minus Age Rule is easy to remember, but it leaves out important information. Two people aged 35 may need very different portfolios: one may have a stable income, no dependants and a retirement goal decades away; the other may be supporting family members and saving for a home purchase in five years.
Equity can offer long-term growth potential, but its value can fall sharply and it may take time to recover. Debt investments are not all risk-free either: depending on the product, they may carry credit risk, interest-rate risk, liquidity limitations or reinvestment risk. A bank fixed deposit, government security, corporate bond and debt mutual fund do not have identical features.
SEBI’s investor education guidance explains that asset allocation should reflect financial goals, risk appetite and investment horizon, and that diversification can reduce concentration risk but cannot guarantee profits or prevent all losses. Read SEBI’s guide to factors to consider before investing before treating any formula as a personal plan.
Should You Use a Different Percentage Instead?
Some investors discuss variants such as 110 minus age or 120 minus age. These formulas produce a higher equity allocation at the same age, but changing the starting number does not make a formula suitable for everyone. A higher equity share can mean larger losses during a market decline. Do not choose a formula simply because you want a higher expected return.
Instead, connect the allocation to the goal. Money needed in the next few years generally should not depend heavily on stock-market performance. Long-term retirement money may be able to tolerate more volatility, depending on your circumstances. Review the plan when your goals, income, family responsibilities or retirement date change. You can also explore the SEBI Investor asset allocation calculator for an additional educational perspective.
How Can You Apply the 100 Minus Age Rule More Carefully?
- Set up a safety buffer first: Keep emergency savings separate from long-term investments and consider suitable health and life insurance where relevant.
- Match assets to goals: Separate short-, medium- and long-term goals instead of using one allocation for every rupee.
- Diversify within asset classes: Equity exposure to a handful of stocks is not the same as a diversified equity portfolio. Debt products also differ in credit quality and duration.
- Check your comfort with losses: If a large temporary decline would cause you to sell in panic, the proposed equity allocation may be too high.
- Rebalance periodically: Market movements can shift your portfolio away from its target. Review it at sensible intervals or after major life changes rather than reacting to every headline.
The 100 Minus Age Rule can help beginners understand the relationship between age and risk, but it should not replace a complete financial plan. For more investing basics and practical tools, visit the Stock Charcha calculators and browse related guides on the Stock Charcha blog.
What Should You Remember Before Following the 100 Minus Age Rule?
Think of the 100 Minus Age Rule as a quick estimate, not a universal law. Your time horizon, financial obligations, income stability, existing assets, risk capacity and risk tolerance matter just as much as your age. A sensible allocation is one you understand, can maintain through market cycles, and can adjust as your life changes. Do not assume the formula guarantees higher returns or protects your capital.
Can You Test Your Understanding of the 100 Minus Age Rule?
Five questions are randomly selected from a topic-specific bank. Refresh the page or choose “New Questions” to try another set.
Where Can You Continue Learning With Stock Charcha?
Disclaimer: This article is for educational purposes only and is not personalised investment advice. Investments in securities and mutual funds are subject to market risks. Review official scheme documents and consider a SEBI-registered investment adviser for advice suited to your circumstances.