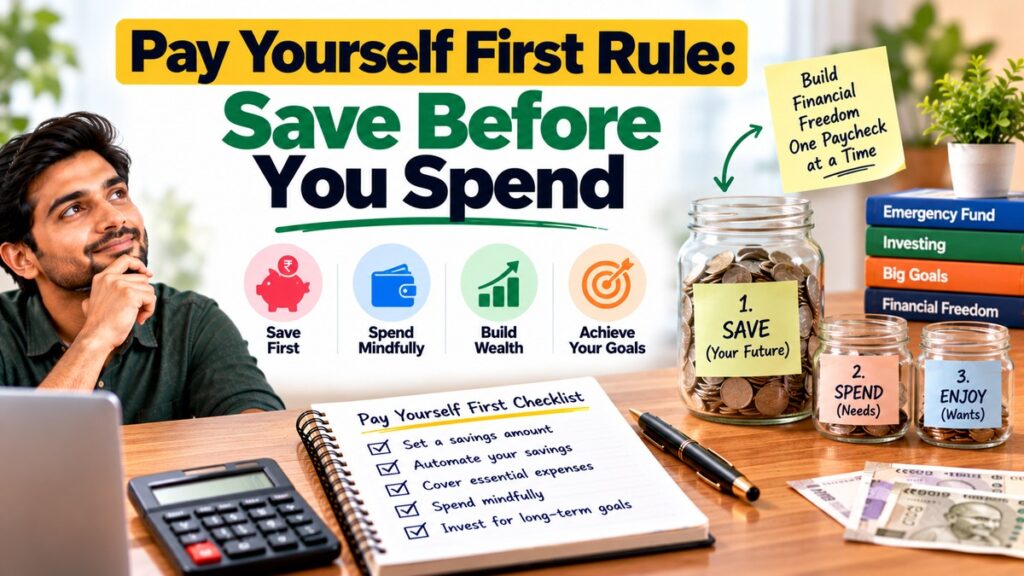
The Pay Yourself First Rule flips the usual money routine: set aside savings when income arrives, then plan your spending with what remains.
The Pay Yourself First Rule is a simple personal-finance habit: when your salary or other income arrives, transfer a planned amount to savings and investments before spending on discretionary wants. Instead of saving whatever happens to be left at the end of the month, you make saving a priority in your budget.
What Is the Pay Yourself First Rule?
Many people intend to save each month, but daily expenses, online shopping, eating out and unexpected purchases can absorb the full salary. The Pay Yourself First Rule changes the order. Saving becomes a planned payment rather than an optional leftover.
For example, if your take-home income is ₹40,000 and you choose to save 15%, you move ₹6,000 to a separate savings or investment account soon after payday. The remaining ₹34,000 becomes the amount you use to manage rent, groceries, bills, transport, family needs and discretionary spending.
The rule does not mean ignoring essential expenses or investing money you may need tomorrow. It means deciding on a sustainable savings amount in advance and making the transfer consistently. If your income varies, you can set a smaller automatic base transfer and add more in stronger months.
How Does It Work in Practice?
- Calculate take-home income. Use the money actually available after payroll deductions, not your gross salary.
- Choose a realistic target. Start with an amount you can maintain after essential expenses and minimum debt payments.
- Automate the transfer. Schedule it for payday or the next working day so you do not rely on memory or willpower.
- Separate your goals. Keep emergency savings distinct from money intended for long-term investing.
- Spend from the remainder. Build the monthly budget around the amount left after your planned savings transfer.
- Review regularly. Increase the amount when income rises or a major expense ends, without making the plan so strict that you repeatedly abandon it.
How Much Should You Pay Yourself First?
There is no single percentage that suits everyone. A commonly used starting point is 10% of take-home pay, but the right amount depends on income, rent, dependants, debt, location and current savings. The Pay Yourself First Rule works best when the target is ambitious enough to make progress but realistic enough to repeat every month.
| Monthly take-home pay | Save 10% | Save 15% | Save 20% |
|---|---|---|---|
| ₹25,000 | ₹2,500 | ₹3,750 | ₹5,000 |
| ₹40,000 | ₹4,000 | ₹6,000 | ₹8,000 |
| ₹60,000 | ₹6,000 | ₹9,000 | ₹12,000 |
| ₹1,00,000 | ₹10,000 | ₹15,000 | ₹20,000 |
If you are currently unable to save 10%, start with 2% or 5% and build gradually. If high-interest debt is putting pressure on your finances, keep required payments current and compare the cost of that debt with the benefits of saving or investing extra money. Do not create a cash-flow crisis just to meet a percentage target.
Try the Pay Yourself First Calculator
Enter your take-home income and target percentage to estimate the amount to set aside each month. This is a budgeting aid, not a recommendation for a particular investment product.
Use take-home income and a target that leaves enough for essential bills, minimum debt payments and realistic day-to-day costs.
Where Should the Money Go First?
The destination depends on the purpose and when you may need the money. The Pay Yourself First Rule is about the habit of allocating money first; it does not mean every rupee should automatically go into the stock market.
- Emergency fund: Build accessible cash for unexpected expenses or an income interruption. A common goal is three to six months of essential expenses, adjusted to your circumstances.
- Near-term goals: Money for fees, a planned purchase or a house deposit in the next few years generally needs lower volatility and ready access.
- Long-term goals: For goals many years away, diversified investments may be appropriate after considering risk tolerance, time horizon and costs.
- Expensive debt: Repaying high-interest borrowing can be an important part of improving your financial position.
Keep emergency money separate from long-term investments that can fall in value. Market-linked investments do not guarantee returns, and you may have to sell at a loss if you invest money that you need urgently.
Pay Yourself First vs. Save Whatever Is Left
| Pay yourself first | Save what is left |
|---|---|
| Savings is planned at the start of the month. | Savings depends on what remains at month-end. |
| Automation reduces the need to remember. | Spending decisions can crowd out savings. |
| You budget around a clear spending limit. | Your spending limit can be unclear. |
| Progress is easier to measure and review. | Contributions may be inconsistent. |
The Pay Yourself First Rule is not magic: an automatic transfer cannot fix a budget where essential costs exceed income. If the numbers do not work, review recurring subscriptions, large fixed costs, debt, and opportunities to increase income before raising the target.
Common Mistakes to Avoid
- Setting an unrealistic target: A very high amount can lead to transfers being reversed or borrowing before payday. Start sustainably.
- Investing the emergency fund in volatile assets: Emergency money needs access and stability, not maximum growth.
- Ignoring irregular expenses: Annual insurance premiums, school fees, repairs and festivals should be budgeted for across the year.
- Never reviewing the plan: Revisit the target after a salary change, new responsibility or change in living costs.
- Confusing saving with investing: Saving usually prioritises access and stability; investing accepts risk in pursuit of potential long-term growth.
- Forgetting protection: Consider appropriate health and life insurance needs, particularly if others depend on your income.
Make the Rule Work With a Monthly Budget
You can combine the Pay Yourself First Rule with a simple budget such as the 50/30/20 framework. Treat the chosen savings transfer as a planned allocation, then check whether essential spending and discretionary expenses fit the remaining amount. The exact percentages can be adjusted to reflect local housing costs, family responsibilities and financial goals.
At the end of each month, check three things: did the transfer happen, did you need to withdraw it again, and was the remaining budget enough? If you had to reverse the transfer, adjust the target instead of treating the month as a failure. Consistency over time matters more than choosing a perfect percentage on day one.
Five-Question Quiz: Pay Yourself First Rule
Check your understanding before putting the habit into practice.
Where Can You Continue Learning With Stock Charcha?
Useful Resources and Related Guides
- 50/30/20 Budget Rule: A Guide for India
- 3 to 6 Months Emergency Fund Rule
- More Finance Rules
- Personal Finance Calculators
- Charcha Knowledge Hub
- Latest Stock Charcha Articles
- SEBI Investor Education
A simple Pay Yourself First Rule routine is to review the transfer after every salary change.
The Pay Yourself First Rule is a habit, not a promise that every month will look identical.
Use the Pay Yourself First Rule to make your savings target visible and repeatable.
A practical Pay Yourself First Rule should protect essential expenses and avoid new high-interest debt.
Use the Pay Yourself First Rule as a repeatable routine, not a rigid rule that ignores real-life costs.
A sustainable Pay Yourself First Rule starts with your actual take-home income and essential expenses.
The Pay Yourself First Rule can be adjusted when rent, family responsibilities or income changes.
Automating the Pay Yourself First Rule helps make the planned transfer before optional spending begins.
The Pay Yourself First Rule should support your emergency fund before you take investment risk.
Review the Pay Yourself First Rule every few months and change the target if your budget no longer works.
The Pay Yourself First Rule works best when savings goals are clear and the monthly amount is realistic.
Treat the Pay Yourself First Rule as a habit that can grow gradually as your income improves.
A useful Pay Yourself First Rule is flexible enough to survive changes in monthly expenses.
Keep the Pay Yourself First Rule aligned with your real budget, rather than chasing a percentage for its own sake.
Key Takeaway
The Pay Yourself First Rule helps turn saving from a good intention into a repeatable action. Choose a realistic percentage of take-home income, automate the transfer, build accessible emergency savings, and match investments to your goals and risk tolerance. Review your plan when life changes, and avoid borrowing just to maintain an arbitrary savings target.
Educational content only; not personalised financial, tax or investment advice. Investment values can rise or fall. Check product terms and consider qualified advice where appropriate.