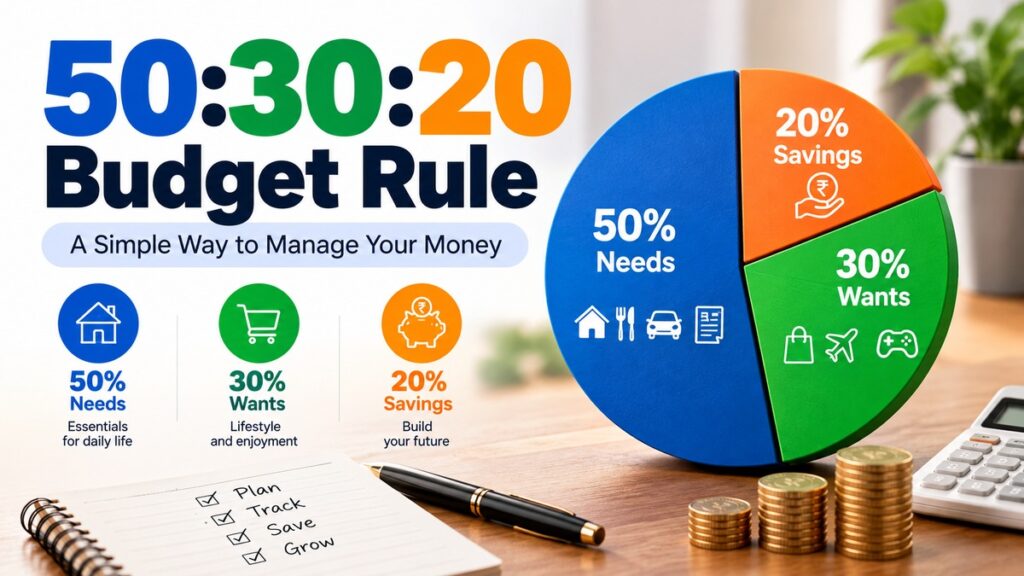
Learn how to divide your income between needs, wants and savings, with practical examples in Indian rupees and a plan you can adapt to your own budget. You can also explore more practical money-management ideas in the Stock Charcha Finance Rules guide.
Watch the Video: Understand the 50:30:20 Rule
Before you build your monthly budget, watch this explainer. Then use the steps below to apply the idea to your own income and expenses.
What Is the 50:30:20 Rule?
The 50:30:20 Rule is a simple budgeting method that divides your take-home income into three broad categories: 50% for needs, 30% for wants and 20% for savings and financial goals. It can help you give every rupee a purpose instead of waiting to see what remains at the end of the month.
Many people receive their salary, pay bills, spend on shopping or food delivery, and plan to save whatever is left. The problem is that the money left over may be little—or nothing. A budget reverses that habit by making saving a planned part of the month.
How Does the 50:30:20 Rule Work?
50% — Needs and essential expenses
Use this portion for costs you need to live and work, such as rent, groceries, electricity, basic phone and internet bills, transport, essential insurance premiums and required loan payments.
30% — Wants and lifestyle
This portion can cover dining out, entertainment, shopping, subscriptions, hobbies and holidays. Enjoying your income matters too; the goal is to plan these expenses instead of letting them quietly take over your budget.
20% — Savings and financial goals
Use this portion to build an emergency fund, save for important goals, repay expensive debt where appropriate, and invest according to your time horizon and risk tolerance. Investing is not the same as keeping cash savings, and market-linked investments can lose value.
Example: Apply the 50:30:20 Rule to a ₹50,000 Salary
Suppose your monthly take-home salary is ₹50,000. Here is how the suggested split would look on paper:
| Budget category | Percentage | Monthly amount | Possible uses |
|---|---|---|---|
| Needs | 50% | ₹25,000 | Rent, groceries, utilities, transport and essential bills |
| Wants | 30% | ₹15,000 | Eating out, movies, shopping and planned travel |
| Savings and goals | 20% | ₹10,000 | Emergency fund, goal-based savings and suitable investments |
| Total | 100% | ₹50,000 | Every rupee has a planned role |
If your salary is ₹30,000, the same illustrative split is ₹15,000 for needs, ₹9,000 for wants and ₹6,000 for savings and goals. Your actual costs may require a different split, particularly if you support family members or live in a high-rent city. To run numbers for your own situation, browse the Stock Charcha financial calculators.
Pay Yourself First: Make Saving a Habit
A practical lesson from the video is to avoid treating savings as an afterthought. When your salary arrives, plan your savings allocation early rather than spending first and hoping money remains later.
- List your take-home income and fixed monthly commitments.
- Set a realistic savings amount and automate a transfer where possible.
- Build an emergency reserve—many people aim for three to six months of essential expenses, adjusted to their circumstances.
- After your emergency reserve is adequate, allocate money to goals and investments suited to your risk profile and time horizon.
- Review actual spending at the end of each month and make one practical improvement.
If you have no emergency savings or are struggling with high-interest debt, it may be sensible to prioritise financial stability before increasing market investments. Your plan should reflect your situation, not a percentage alone. For more beginner-friendly explanations of money and investing concepts, visit the Charcha Knowledge Hub.
Why Starting Early Can Matter
Starting to save and invest early gives your money more time to potentially grow. Compounding means that returns may themselves generate returns over time. However, market returns are not fixed, and examples cannot promise a particular future value.
For example, a young worker who begins with a manageable monthly contribution and increases it as income grows may build a useful long-term habit. Someone who starts later can still make progress, but may need a different contribution rate, timeline or goal.
Common Budgeting Mistakes to Avoid
- Saving only at month-end: set a savings plan when income arrives.
- Ignoring small recurring expenses: review subscriptions, delivery orders and impulse purchases.
- Taking on unaffordable EMIs: consider the full cost of ownership, including fuel, maintenance, insurance and repairs—not just the monthly instalment.
- Investing without an emergency reserve: keep accessible money for unexpected expenses.
- Assuming all debt is the same: assess the interest rate, repayment burden, purpose and risk before borrowing.
- Following the split blindly: adapt the budget when essential costs, dependants or income change.
Can You Adjust the 50:30:20 Rule?
Yes. A person living with family may spend less on housing than someone renting in Mumbai, Bengaluru or Delhi. A new parent may have higher essential costs, while someone paying down expensive debt may need to redirect part of the wants budget temporarily.
Use the 50:30:20 Rule as a guide for reviewing trade-offs. If needs take up 60% of your income today, start by tracking expenses and identifying changes that are realistic. You do not need to make a perfect budget in one month; consistency is more useful than a split you cannot sustain.
Quick Quiz: Test Your Budgeting Knowledge
A fresh set of five questions is selected from our 50:30:20 Rule question bank when this page loads. Refresh the page to try a different set.
Frequently Asked Questions
What is the 50:30:20 Rule in simple words?
It is a budgeting guideline that suggests dividing take-home income into 50% for needs, 30% for wants and 20% for savings and financial goals.
Can I follow this budgeting method on a ₹25,000 salary?
Yes, you can use it as a starting point. On ₹25,000, the illustrative amounts are ₹12,500 for needs, ₹7,500 for wants and ₹5,000 for savings and goals. Adjust them to your actual essential expenses.
Should I invest the full 20% every month?
Not necessarily. The category includes savings and financial goals, not only market investments. Consider emergency savings, expensive debt, time horizon and risk tolerance before deciding how much to invest.
Is the 50:30:20 Rule suitable for everyone?
No single budget works for every household. Use it as a framework and adapt it to your income, location, family responsibilities, debt and goals.
Continue Learning with Stock Charcha
Good money management starts with awareness and improves through consistent habits. Explore these Stock Charcha resources to keep learning and put the ideas into practice.
For additional guidance on budgeting, saving and managing income, see the SEBI Investor education resource on managing income and expenses.
Educational disclaimer: This article is for general educational purposes only and does not constitute personalised financial or investment advice. Savings products and investments have different risks, terms and liquidity. Market-linked investments can lose value. Review official product terms and consider a qualified financial professional for advice suited to your circumstances. The budgeting percentages are illustrative guidelines, not guaranteed outcomes.