Learn why a home loan EMI that looks affordable on paper can still strain your monthly budget once maintenance, family expenses, savings and emergencies are included.
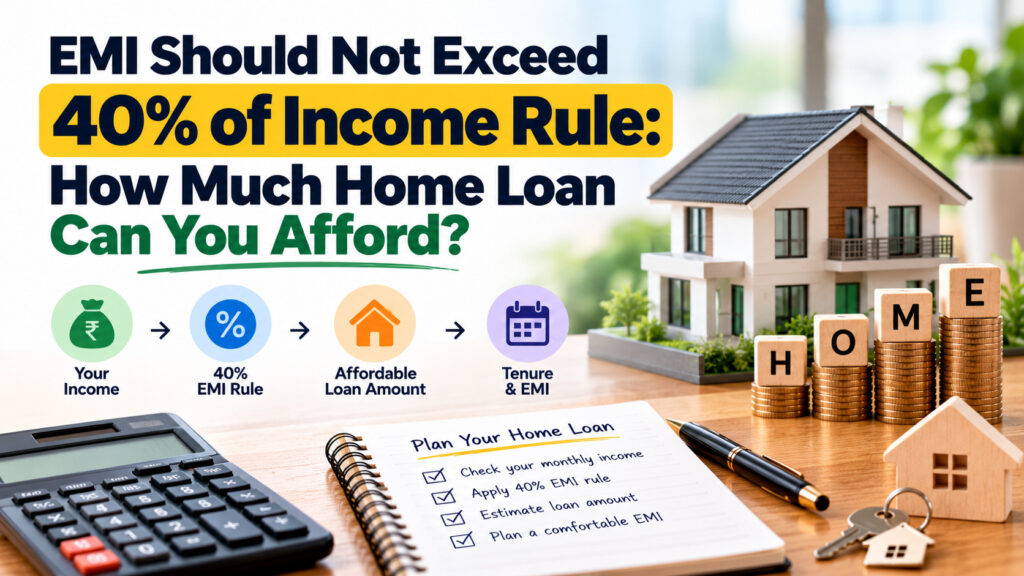
When you apply for a home loan, a lender may assess how much of your income can go towards EMIs. But the maximum loan a bank is willing to offer is not necessarily the amount that fits comfortably into your life. The EMI Should Not Exceed 40% of Income Rule is a useful starting point for checking affordability, not a guarantee that a loan is safe for every household.
Your budget needs to cover more than the loan instalment. Society maintenance, property tax, insurance, repairs, groceries, childcare, support for parents and long-term goals all matter. Before deciding on a property, explore your numbers alongside the Stock Charcha calculators and our guide on building a financial plan around your goals.
Watch the video, then use the example and calculator below to test your own monthly budget.
What Does the EMI Should Not Exceed 40% of Income Rule Mean?
The rule suggests keeping your monthly loan EMIs within roughly 40% of your take-home household income. For a household bringing home ₹2,50,000 per month, 40% is ₹1,00,000. That is a ceiling for a quick check—not a target you must use.
Some households may need a much lower ratio, especially if they have children, dependants, variable income, other loans or major goals approaching. Also distinguish the EMI ratio from the total cost of owning a home. The latter includes expenses that do not appear in the loan EMI.
Why Can a 32% Home Loan EMI Still Feel Expensive?
Consider the illustrative case discussed in the video: a dual-income couple, aged around 34 and 32, with one child and combined take-home income of ₹2.5 lakh per month. They are considering a ₹1.2 crore home and a ₹1 crore home loan at an assumed 8.5% interest rate over 25 years.
At those loan assumptions, the EMI is approximately ₹80,600 per month. That is about 32% of their take-home income. It may look manageable at first glance, but it is only one part of the monthly housing bill.
| Monthly housing cost | Illustrative amount |
|---|---|
| Home loan EMI | ₹80,600 |
| Society maintenance | ₹8,000 |
| Property tax (monthly equivalent) | ₹2,000 |
| Home insurance | ₹1,000 |
| Repairs and maintenance reserve | ₹3,000 |
| Total estimated monthly housing cost | ₹94,600 (about ₹95,000) |
The total housing cost is about 38% of ₹2.5 lakh. This is why looking only at the EMI can understate the actual monthly commitment. These amounts are examples from a case study; costs will differ by property, city, lender and household.
What Happens When You Add Everyday Expenses and Other Goals?
The same household also has several other commitments. For illustration, assume ₹30,000 goes to SIP investments, ₹70,000 to regular household spending, ₹15,000 to supporting parents and ₹20,000 to childcare and related costs. Add those to the estimated ₹94,600 housing cost and the total reaches about ₹2,29,600 per month.
An SIP is usually a flexible investment contribution that can be reduced or paused, although doing so may delay goals. A home loan EMI is a contractual repayment obligation. If income falls, the EMI generally remains due. That difference matters when judging whether a home is affordable.
Could a Job Loss Turn the EMI Into a Financial Trap?
Stress-test the decision before signing the loan. If one partner temporarily loses a job and household income drops from ₹2.5 lakh to ₹1.25 lakh per month, the ₹95,000 housing cost alone would consume about 76% of the remaining income. There would be very little room for food, childcare, parents’ support and other essential expenses.
In such a situation, the family might have to pause SIPs, delay goals, draw down fixed deposits or emergency savings, or borrow at a high cost. These are not automatic outcomes, but they show why affordability should be assessed against a difficult scenario—not only against today’s income.
- Test whether the household can manage if one income stops for several months.
- Build an emergency fund suited to essential expenses, job stability and dependants.
- Account for other EMIs, insurance premiums, school fees and foreseeable repairs.
- Leave room for interest-rate changes if the loan has a floating rate.
Would a Lower-Cost Home Create More Financial Breathing Room?
The video explores a less expensive alternative: instead of a ₹1.2 crore property funded by a ₹1 crore loan, consider a home around ₹95 lakh and a loan of about ₹75 lakh. At the same assumed 8.5% rate and 25-year tenure, the EMI would be roughly ₹60,400 per month—not ₹55,000—before adding other housing costs. With similar non-EMI costs, total housing expenses could be around ₹74,000 per month. Actual loan quotes and property expenses may differ.
That reduces the total housing burden and can leave more space for savings, emergency reserves and family goals. A smaller loan does not automatically make a purchase right for everyone, but comparing a few realistic price points is more useful than stretching to the maximum amount a lender offers.
How Can You Calculate Your Own EMI-to-Income Ratio?
Enter your monthly take-home household income, all monthly EMIs and estimated non-EMI housing costs. This quick calculator helps you separate the loan instalment ratio from the broader cost of owning a home.
This is a budgeting aid, not a lender eligibility check or financial recommendation. The 40% threshold is a rule of thumb, not a universal standard.
What Should You Check Before Taking a Home Loan?
- Calculate the full housing cost. Include EMI, society charges, taxes, insurance, repairs and any recurring property costs.
- List every other commitment. Include existing loan payments, household expenses, dependent support, childcare and important goals.
- Keep an emergency buffer. Avoid using every available rupee for the down payment if that leaves you without accessible reserves.
- Run a reduced-income scenario. Ask what happens if one income stops, a bonus disappears or costs rise.
- Compare more than one property budget. A lower loan may protect flexibility and help you keep investing toward other goals.
- Read the loan terms carefully. Check the interest type, reset conditions, tenure, fees, prepayment terms and consequences of missed payments.
For independent investor education and general financial awareness, refer to SEBI Investor. For home-loan-specific decisions, review the actual offer documents and consider advice from a qualified professional who understands your full financial situation.
Can You Test Your Understanding of the 40% EMI Rule?
Answer these five quick questions. Select “New questions” to generate another set from the question bank.
Frequently Asked Questions
Is 40% of income a strict rule for every borrower?
No. It is a rule of thumb, not a universal limit. Household expenses, dependants, income stability, other loans, savings and financial goals all affect what is comfortable.
Should I count only the home loan EMI?
No. Track the EMI separately, but also include maintenance, property tax, insurance and repairs when estimating the full cost of owning the property.
Is a home loan affordable if the bank approves it?
Approval indicates that the lender is willing to offer credit under its criteria. It does not guarantee that the repayment will fit your lifestyle and future goals comfortably.
What is a more comfortable home loan EMI ratio?
Some households may prefer an EMI below 30% of take-home income, especially when they have dependants or uncertain income. There is no single percentage that works for everyone; evaluate the full budget.
Should I stop investing to pay a larger EMI?
Do not decide based on the ratio alone. Compare the trade-offs, preserve an appropriate emergency fund and consider whether the home price or loan amount can be reduced instead.
Where Can You Continue Learning With Stock Charcha?