Understand the income-multiple rule for term insurance, estimate a starting cover amount, and learn why your family’s actual needs matter more than a shortcut.
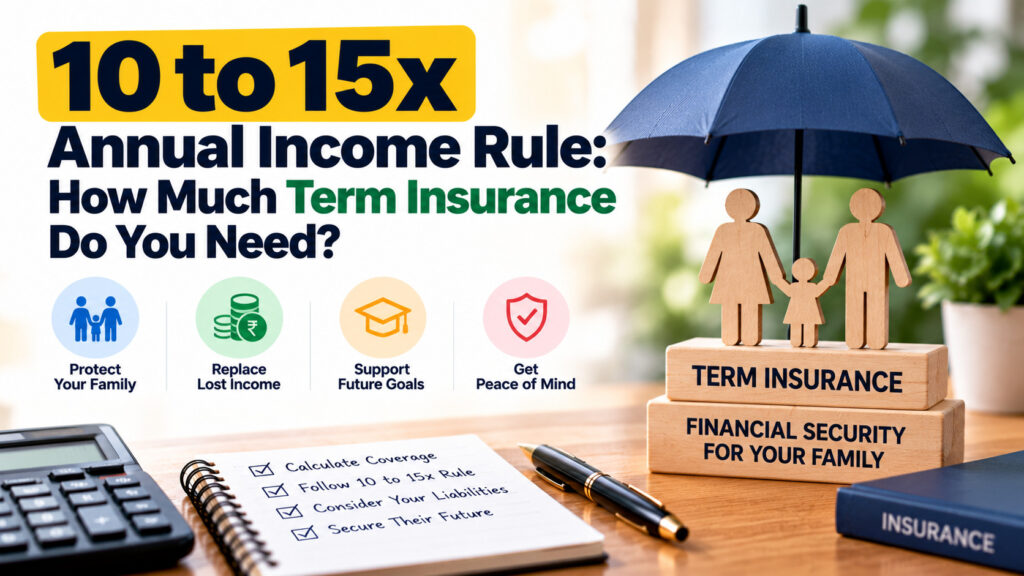
If your family depends on your income, life insurance can help protect them financially if you die during the policy term. The 10 to 15x Annual Income Rule is a simple starting point: consider term insurance cover equal to around 10 to 15 times your annual income. It is not a personalised answer for every family, but it can help you start estimating the protection gap.
For example, someone earning ₹12 lakh a year might use ₹1.2 crore to ₹1.8 crore as an initial range. The right amount may be higher or lower depending on outstanding loans, future family expenses, existing assets, other insurance and the number of people who rely on that income. Read this alongside your wider personal-finance rules and use the Stock Charcha calculators to plan related goals.
Watch the video, then use the calculator and checklist below to estimate your family’s protection needs.
What Does the 10 to 15x Annual Income Rule Mean?
The rule suggests that a person who earns income and has financial dependants should consider a term life cover of roughly 10 to 15 times their annual income. Annual income generally means your yearly earnings; for a more useful household estimate, decide whether you are using gross income or take-home income and stay consistent. The rule is a starting benchmark, not an official regulatory requirement or a guarantee that the cover will be sufficient.
Why use a multiple? A family may need money for everyday living costs, children’s education, rent or housing expenses, outstanding liabilities and time to adjust after the loss of an earner. A lump sum can help replace some of the income that would otherwise have supported those needs. However, the money required depends on the family’s circumstances and how the proceeds are managed.
Why Is Term Insurance Important if Your Family Depends on You?
Term insurance is life cover for a specified period. If the insured person dies while the policy is active and the claim meets the policy terms, the insurer pays the stated death benefit to the nominee or beneficiary. It is designed primarily for financial protection, rather than as a savings or investment product. Premiums, exclusions, disclosures and claim conditions differ by policy, so read the policy wording carefully.
Consider a household where one person earns most of the income and pays the home loan, school fees and regular bills. If that income disappears, those expenses do not disappear with it. A suitable life cover can give surviving family members funds to manage immediate expenses, repay some liabilities or support longer-term goals. It cannot replace a person, and no insurance amount removes every financial or emotional difficulty, but it may reduce the financial shock.
People with no financial dependants may have a different need for life cover. On the other hand, a person with children, a non-earning spouse, dependent parents or a large loan may need to assess protection carefully. Review the need whenever there is a major life change, such as marriage, a child, a new loan, a change in income or a dependent becoming financially independent.
How Can You Calculate a Starting Term Insurance Cover?
Start with annual income, multiply it by 10 and 15 to create a broad range, and then look beyond the rule. A needs-based estimate can add future family expenses and liabilities, subtract resources that can realistically support dependants, and account for existing life cover. Avoid counting the same need twice.
The calculator’s adjusted figure simply subtracts the cover and assets you enter from the 10x and 15x estimates, then adds the loan amount entered. This simplified method does not model inflation, future education costs, taxes, investment returns or the timing of cash flows. Use it as a conversation starter—not the final amount to buy.
What Can the Income-Multiple Rule Miss?
Income is useful, but it does not fully describe a family’s financial obligations. Two people earning ₹15 lakh a year may need very different cover if one has no dependants and no debt while the other supports children and parents and has a long home loan.
- Outstanding liabilities: Consider a home loan, personal loan or other debt that could burden surviving family members.
- Future goals: Estimate important future costs, such as education, and how long dependants may need financial support.
- Existing resources: Include savings or investments only to the extent they are available for these needs and are not already earmarked for another goal.
- Existing insurance: Check employer-provided group life cover and individual policies. Group cover may end when employment changes, so do not assume it will always continue.
- Inflation and time: A fixed amount may buy less in the future. Consider how long the family may need support rather than looking only at today’s expenses.
For a more detailed assessment, the Human Life Value approach considers earning potential and the financial contribution a person would have made to their dependants. It can be a useful complement to the simple multiple. The 10% Rule for Insurance Premium is a separate budgeting guideline about premiums; it does not determine how much life cover a family needs.
How Can You Avoid Common Term Insurance Mistakes?
- Choosing cover only because a salesperson suggests it. Ask how the amount was calculated and compare it with your own needs.
- Buying too little cover. A low premium can look attractive, but the sum assured may not be enough for dependants and liabilities.
- Delaying without reviewing the risk. Age and health can affect eligibility and pricing. Understand the options available to you rather than assuming you can buy the same cover later.
- Giving incomplete or inaccurate information. Answer questions about health, smoking, occupation, income and existing policies honestly. Material misrepresentation can create claim problems.
- Ignoring exclusions and policy terms. Read definitions, exclusions, premium-payment terms, revival rules and claim requirements before buying.
- Confusing life cover with investment returns. Compare products based on the protection you need and understand what each policy is designed to do.
- Relying only on employer cover. Check whether cover is portable or tied to your job and whether the amount is adequate for your family.
- Failing to update the nominee. Review nominee details and keep policy documents accessible to the family.
- Not reviewing cover after life changes. Revisit the amount after a child, a major loan, a change in income or other significant event.
How Do You Choose and Maintain a Term Insurance Policy?
Compare the policy terms, premium affordability, insurer information, available claim support and the disclosures required during application. Do not select a policy based only on a headline price or one comparison metric. A lower premium is not useful if the cover amount, policy term or conditions do not match your needs.
Choose a policy term that reflects the period during which others depend on your income or liabilities remain. Keep premiums affordable for the long term, and make sure the policy details and payment reminders are available to a trusted family member. Review your cover periodically, but do not cancel an existing policy until replacement cover is approved and active, if you decide to replace it.
For official consumer information, visit the Insurance Regulatory and Development Authority of India (IRDAI) website and read the policy document supplied by the insurer. You can also explore the Stock Charcha Knowledge Hub for broader financial education.
Can You Test Your Understanding of the 10 to 15x Rule?
Try these five questions. Choose “New questions” to get another set from the question bank.
Frequently Asked Questions
Is 10 to 15 times annual income a mandatory rule?
No. It is a common rule of thumb, not a universal requirement or an official minimum. Estimate your family’s actual needs before deciding on cover.
Is term insurance the same as health insurance?
No. Term life insurance provides a death benefit subject to policy terms. Health insurance helps cover eligible medical expenses under its policy conditions.
Should I subtract existing investments from the cover estimate?
Only count assets that are realistically available for dependants’ needs. Avoid counting funds already earmarked for other goals, and remember that values can change.
Can employer-provided life insurance be enough?
It may contribute to your protection, but check the amount, policy terms and whether it continues if you leave the job. Do not assume employment cover is permanent.
When should I review my term insurance?
Review it after major life events, including marriage, a child, a new loan, income changes or a change in who depends on you financially.
Where Can You Continue Learning With Stock Charcha?