Build a savings habit before the month’s spending takes over. Learn how the 80:20 Rule works, try a simple income split calculator, and adapt the numbers to your real household costs.
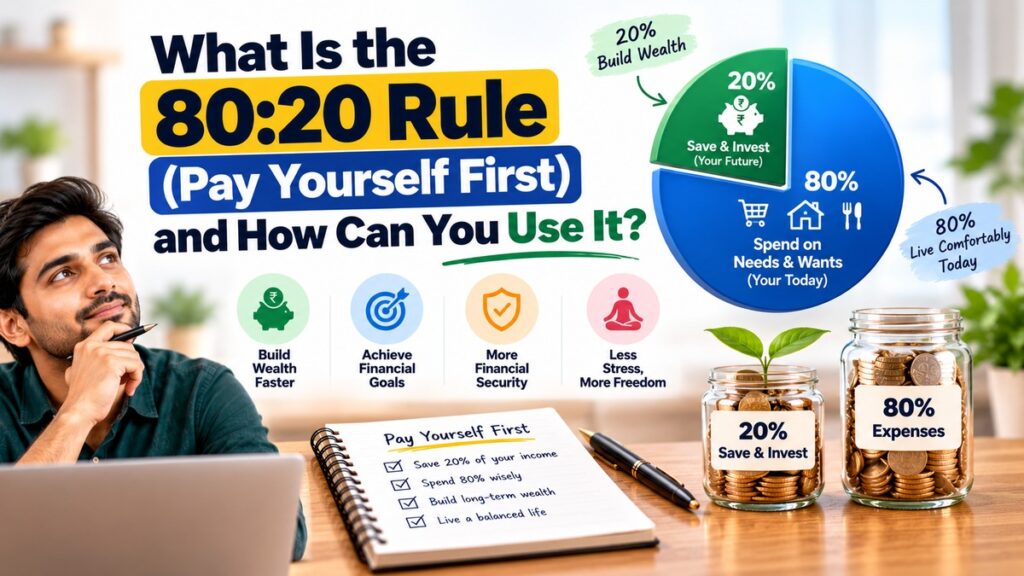
Your salary arrives on the 1st, rent and bills go out, food and travel take their share, and by the end of the month the savings account has barely moved. If that sounds familiar, the 80:20 Rule (Pay Yourself First) offers a simple change: set aside 20% of your take-home income for savings and investments first, then plan your spending around the remaining 80%.
It is a budgeting habit, not a law that every household must follow. Someone with high rent, family responsibilities or an irregular income may need to start with a smaller savings percentage and build up gradually. The goal is to make saving intentional instead of waiting to see what is left over.
The supplied video discusses the 80:20 principle in a study context. This article applies the budgeting version: save first, then spend what remains.
What Does the 80:20 Rule Mean for Your Monthly Income?
The budgeting version of the 80:20 Rule divides your take-home income into two broad buckets. Aim to direct 20% towards savings, investments and important future goals, while using the remaining 80% for living costs and discretionary spending. “Pay yourself first” means making the savings transfer early—ideally soon after income arrives—rather than treating savings as an afterthought.
For example, if your take-home salary is ₹60,000, the 20% target is ₹12,000 and the remaining 80% is ₹48,000. If your income is ₹1 lakh, the corresponding amounts are ₹20,000 and ₹80,000. These are targets to plan around, not guarantees that the split will fit every household.
How Can You Calculate Your Own 80:20 Split?
Use this simple calculator to estimate the amount you could set aside each month. Enter your monthly take-home income and adjust the savings percentage if 20% is not realistic yet. The calculation is a starting budget, so include all recurring household expenses before deciding whether the spending amount is workable.
Once you have the result, compare the spending amount with rent or home-loan EMI, groceries, utilities, transport, insurance premiums, dependants’ costs and debt repayments. If essential costs alone exceed the suggested 80%, do not skip necessary bills to force the formula. Start with a savings rate you can sustain and review it when your income or expenses change.
What Should Count as the 20% You Pay Yourself First?
The 20% is not necessarily one single investment. It can be divided across goals according to when you will need the money and how much uncertainty you can accept. A practical order is to build a cash buffer for emergencies, address expensive debt, and then allocate money towards medium- and long-term goals.
- Emergency savings: Keep accessible money for unexpected bills or income disruption. The right buffer depends on job stability, dependants and essential monthly costs.
- High-interest debt: Paying down expensive credit-card or personal-loan balances may be more urgent than increasing market-linked investments.
- Short-term goals: Set aside money for expenses expected in the next few years, such as education fees or a planned move, using options appropriate to the time horizon.
- Long-term goals: Retirement or other long-term investing may fit here once urgent needs and your emergency buffer are addressed. Investments can fall in value, so match the product to the goal and risk you can bear.
For investment goals, use the relevant Stock Charcha calculators to test assumptions rather than treating a projection as a promise. Market-linked returns vary, and no calculator can guarantee the outcome.
How Is Pay Yourself First Different From Saving Whatever Is Left?
With a “leftover” approach, spending usually happens first and saving depends on what remains. That can work for some people, but it makes savings unpredictable. Pay yourself first reverses the order: decide on a reasonable amount, transfer it automatically after payday, and use the balance to run the month.
Automation can reduce the number of decisions you need to make. You might schedule a transfer to a separate savings account on salary day, or set up recurring contributions for a suitable goal. Check your account balance and upcoming bills first; an automated transfer should not push you into overdrafts, missed payments or fresh borrowing.
Does the 80:20 Rule Work for Every Salary and Household?
No single percentage works equally well for everyone. A person living with family and paying few household costs may be able to save more than 20%. Someone paying a large city rent, supporting parents, raising children or repaying a home loan may have less room. Irregular earners may find it more useful to set aside a percentage of each payment rather than rely on a fixed monthly amount.
Use the 80:20 Rule as a direction, not a test of discipline or personal worth. If you currently save nothing, even 5% or 10% set aside consistently can be a meaningful first step. When income rises, consider directing part of the increase to savings before your regular spending expands to match it.
Also distinguish saving from investing. Savings are generally meant to preserve access to money for nearer-term needs; investments are chosen for specific goals and can carry market, credit, liquidity or other risks. Before investing, understand the product, costs, time horizon and possibility of loss. SEBI’s Investor website offers investor-education resources, while the Reserve Bank of India provides official information about banking and financial awareness.
How Can You Make the 80:20 Rule Stick Without Feeling Restricted?
- Use take-home income. Base the split on the amount that actually reaches your account after payroll deductions, and be consistent about what you include.
- Separate the buckets. Keep goal money distinct from everyday spending where practical, so it is easier to track progress.
- Budget for irregular costs. Annual insurance premiums, school expenses, repairs and festivals are predictable even if they do not arrive every month. Set aside a monthly amount for them.
- Review without blame. Compare your plan with actual spending at month-end. If essential expenses have changed, revise the budget instead of relying on credit to maintain an unrealistic target.
- Raise the target gradually. A sustainable 10% savings rate is more useful than a 20% target that repeatedly collapses and leaves you short of cash.
Stock Charcha focuses on practical financial education and calculators that let you check the numbers yourself. Use the 50:30:20 budget rule guide to compare another way of dividing income, and explore the emergency fund rule when deciding how much of your savings should remain accessible. If a linked page has moved, use the site’s finance-rules section to find the current version.
What Are the Limits of the 80:20 Rule?
The rule is intentionally simple, which means it cannot replace a full household budget. It does not account for every difference in taxes, cost of living, family structure, debt interest rates or financial goals. It also does not tell you which savings or investment product to choose. The right allocation depends on when you need the money and what risks you can accept.
Do not borrow at a high interest rate just to claim that you saved 20%, and do not ignore essential insurance or minimum debt payments to reach a target. If your finances are under pressure, prioritise immediate needs, seek reliable support where appropriate, and return to the percentage target when it becomes workable.
Can You Test What You Have Learned About the 80:20 Rule?
Answer five randomly selected questions below. Choose “New questions” to get a different set from the question bank.
What Is the Most Useful Way to Start?
Choose a savings percentage you can sustain, move that amount aside shortly after payday, and build the rest of your budget around the money that remains. The 80:20 Rule works best as a repeatable habit—not a rigid promise to save exactly 20% regardless of circumstances. Review the numbers regularly and adjust them as your life changes.
Where Can You Continue Learning With Stock Charcha?