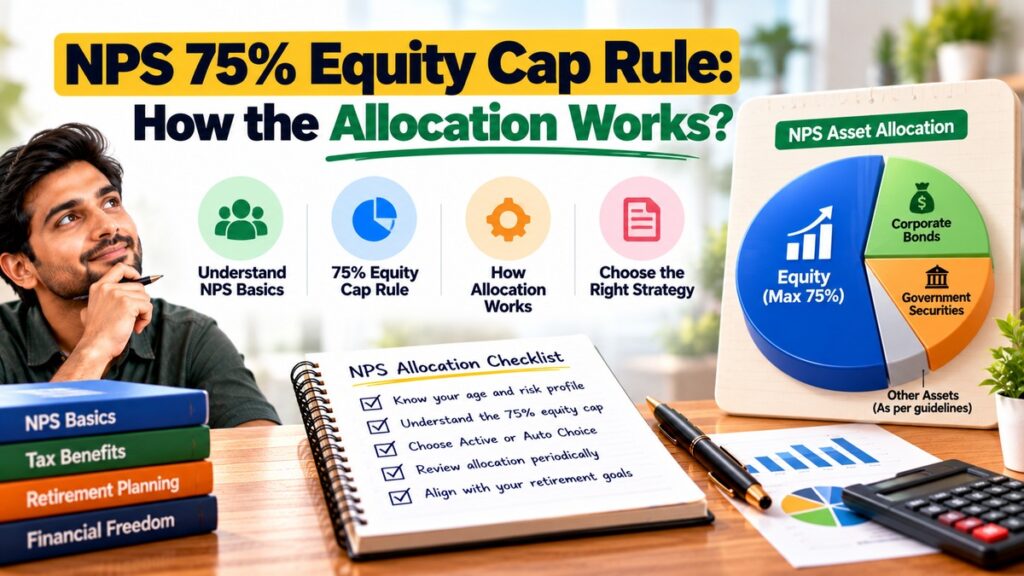
Understand the NPS 75% Equity Cap Rule discussed in the supplied video, see how contributions may be divided, and learn why retirement investing requires attention to risk, time horizon and current NPS rules.
Watch the Video
This article follows the supplied Bengali-language video about the NPS 75% Equity Cap Rule, an allocation described as 75% equity, 15% government securities and 10% corporate bonds. The video presents it as an aggressive active-choice mix intended for long investment horizons. The exact eligibility and allocation limits for the NPS 75% Equity Cap Rule depend on applicable NPS rules and subscriber category, so verify current rules with official sources before making a choice.
What Is the NPS 75% Equity Cap Rule?
The NPS 75% Equity Cap Rule refers here to the allocation described in the video: up to 75% of the portfolio in equity, with the remaining 25% split between government securities and corporate bonds. The video labels this an aggressive active-choice asset allocation, rather than an automatic allocation that every NPS account receives.
To understand the NPS 75% Equity Cap Rule, consider the video’s example: a ₹20 lakh NPS balance would be allocated as follows if the stated percentages applied to the full balance:
| Asset class | Illustrative allocation | Amount from ₹20 lakh | General role |
|---|---|---|---|
| Equity | 75% | ₹15,00,000 | Long-term growth potential, with substantial market volatility. |
| Government securities | 15% | ₹3,00,000 | Exposure to government debt; prices can still change when interest rates move. |
| Corporate bonds | 10% | ₹2,00,000 | Debt issued by companies, with credit and interest-rate risks. |
| Total | 100% | ₹20,00,000 | Illustrative split only. |
How Would a ₹10,000 Monthly Contribution Be Split?
The NPS 75% Equity Cap Rule can also be illustrated with the video’s monthly contribution example. Applying the same illustrative percentages to ₹10,000 gives ₹7,500 in equity, ₹1,500 in government securities and ₹1,000 in corporate bonds. Actual NPS contributions and investments are subject to your selected scheme, applicable rules, charges and account arrangements.
| Asset class | Allocation | Illustrative share of ₹10,000 |
|---|---|---|
| Equity | 75% | ₹7,500 |
| Government securities | 15% | ₹1,500 |
| Corporate bonds | 10% | ₹1,000 |
| Total | 100% | ₹10,000 |
What Do the Three Asset Classes Do?
1. Equity: growth potential and volatility
Under the NPS 75% Equity Cap Rule example, equity investments provide exposure to shares and can support long-term growth, but they are also the most visibly volatile part of the portfolio. A market decline can reduce the value of the equity allocation, sometimes substantially. Past returns quoted in the video—such as 11% to 15% annually—are not guaranteed future returns and should not be used as a promise in a retirement plan.
2. Government securities: debt-market exposure
In the NPS 75% Equity Cap Rule example, government securities form the defensive debt allocation described in the video. Government securities issued by the Government of India generally have very low sovereign credit risk in rupee terms, but their market prices can fall when interest rates rise. A government-bond allocation is therefore not literally “zero risk” in every sense, and the return is not fixed at the figures quoted in the video unless the specific instrument and terms support that conclusion.
3. Corporate bonds: income with credit risk
Corporate bonds are the third component of the NPS 75% Equity Cap Rule example and are debt instruments issued by companies. Their returns depend on the issuer, credit quality, maturity, interest rates and market conditions. They can offer yields above government securities partly because investors take additional risks. The video’s broad return figures of 7% to 9% are illustrative claims, not assured returns for every corporate-bond allocation.
Try the NPS Allocation Calculator
Use this calculator to explore the NPS 75% Equity Cap Rule and see how a balance or monthly contribution would be split using the video’s illustrative 75/15/10 mix. It only calculates allocation amounts; it does not estimate future returns or confirm whether the mix is currently permitted for your NPS account.
Illustrative allocation only, based on the percentages in the supplied video.
What About Returns and Compounding?
For the NPS 75% Equity Cap Rule, the video gives an illustrative overall return estimate of around 10.75% for the combination and discusses higher potential long-term growth from equity. These figures are not a reliable forecast: asset returns vary over time, and a portfolio’s actual return depends on market performance, the selected schemes, fees, contribution timing and allocation changes.
When evaluating the NPS 75% Equity Cap Rule, remember that compounding can help a retirement corpus grow when returns are reinvested over many years, but it also works alongside volatility. A higher equity share may increase long-term growth potential while increasing the risk of losses near retirement. Consider using a range of scenarios rather than relying on one annual-return assumption.
Does the Equity Cap Change With Age?
The supplied video describes age-related reductions in equity under active choice for the NPS 75% Equity Cap Rule, including a claim that equity is reduced as a subscriber gets older. However, its narration includes inconsistent percentages and age thresholds, so those exact figures should not be copied into a personal plan without verification.
Current NPS allocation rules relevant to the NPS 75% Equity Cap Rule can differ by subscriber category, investment choice and scheme option. Check the latest rules and scheme information from the Pension Fund Regulatory and Development Authority (PFRDA) and the NPS Trust before choosing or changing your allocation.
Who Might Consider a Higher Equity Allocation?
A higher equity allocation under the NPS 75% Equity Cap Rule may be worth evaluating for an investor with a long time horizon, stable finances and the ability to tolerate market falls without abandoning the plan. It is not automatically the best choice for every young subscriber. Goals, income stability, other assets, dependants and risk tolerance matter as much as age.
When considering the NPS 75% Equity Cap Rule, sequence-of-returns risk becomes especially important as retirement approaches: a large market fall shortly before withdrawals can have a lasting effect. The video suggests reducing equity exposure several years before retirement, but there is no single timing rule that suits everyone. Review the applicable NPS options and consider a gradual, rules-based approach rather than trying to predict when the market is high.
Benefits and Limitations of the 75/15/10 Example
| Potential benefit | Limitation or risk |
|---|---|
| Large equity allocation offers long-term growth potential. | Equity markets can fall sharply and take time to recover. |
| Government securities diversify the portfolio away from shares. | Bond prices can fluctuate with interest rates and inflation can reduce purchasing power. |
| Corporate bonds add another source of debt exposure. | Corporate issuers may face credit downgrades or default; yields are not guaranteed. |
| A fixed percentage split is easy to understand. | It may not match your risk capacity, account eligibility or current NPS rules. |
Before You Choose an NPS Allocation
- Confirm the active-choice options and equity limits that apply to your subscriber category.
- Read the scheme information and understand the underlying investment exposure.
- Do not treat historical or quoted returns as guaranteed.
- Check how much market volatility you could tolerate without changing course at the wrong time.
- Review the effect of charges, taxes and withdrawal rules using current official information.
- Reassess the allocation when your goals, income, time horizon or risk tolerance change.
Use the NPS 75% Equity Cap Rule as a starting point for understanding the video’s allocation, not as a universal recommendation. Recheck the NPS 75% Equity Cap Rule against current official scheme rules, and assess the NPS 75% Equity Cap Rule in light of your retirement timeline and ability to withstand losses.
Before applying the NPS 75% Equity Cap Rule, compare the NPS 75% Equity Cap Rule example with your own time horizon, risk tolerance and current official scheme rules. The NPS 75% Equity Cap Rule is an educational illustration, not a guaranteed-return strategy.
Test Your Understanding: NPS 75% Equity Cap Rule Quiz
Answer these five questions to check your understanding of the NPS 75% Equity Cap Rule example and the key risks.
1. What allocation does the video discuss?
2. In a ₹20 lakh balance, what is the illustrative 75% equity amount?
3. Are government securities completely risk-free in every sense?
4. What should you check before choosing the allocation?
5. How should the video’s return figures be treated?
Choose one answer for each question, then check your answers.
Where Can You Continue Learning With Stock Charcha?
Explore these resources to continue learning about financial planning and investing.