The mortgage payment is not the same as rent. Compare the costs you do not recover from renting with the unrecoverable costs of owning before making a housing decision.
Watch the Video First
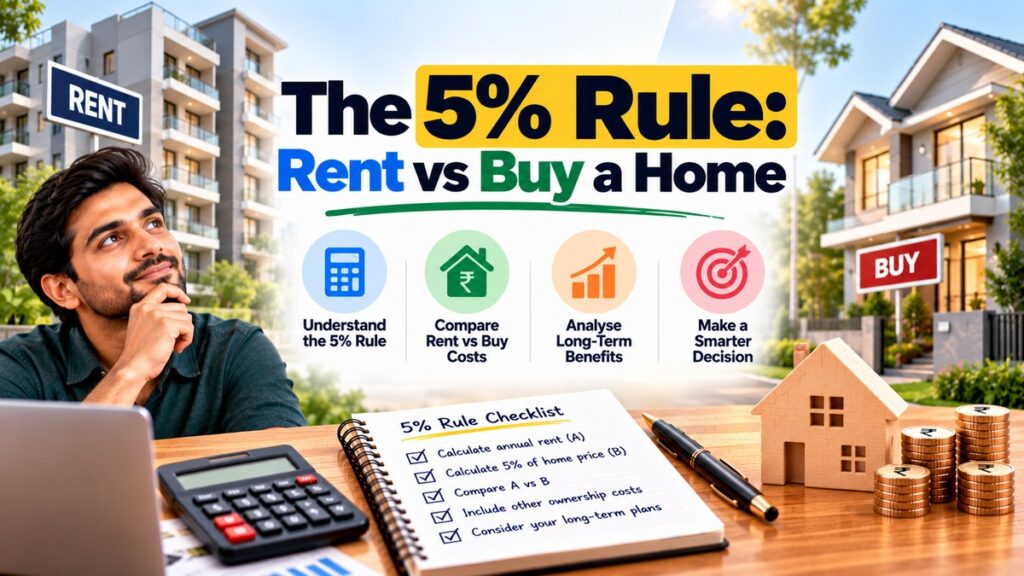
This guide follows the supplied video’s central idea: compare the total unrecoverable costs of renting with the total unrecoverable costs of owning—not rent against the full mortgage payment.
The 5% Rule for Rent vs Buy is a quick way to estimate the annual unrecoverable cost of owning a home. In the video’s framework, these costs are approximated as 1% of home value for property taxes, 1% for maintenance and 3% for cost of capital. Together, these assumptions create the 5% estimate.
What Does the 5% Rule Mean?
A mortgage payment contains two different things: interest and principal repayment. Interest is a cost with no associated residual value, while principal repayment generally builds equity in the home. Treating the entire mortgage payment as if it were rent makes the comparison misleading.
The 5% Rule for Rent vs Buy instead estimates costs that do not directly create recoverable asset value. For a renter, rent is an unrecoverable cost. For an owner, the video identifies property taxes, maintenance and cost of capital as the main simplified components.
How Is the 5% Rule Calculated?
| Component in the video’s model | Illustrative annual estimate | Why it is included |
|---|---|---|
| Property taxes | 1% of home value | Taxes paid to own the property are not recovered by selling it. |
| Maintenance | 1% of home value | Upkeep and repairs are expenses incurred to maintain the property. |
| Cost of capital | 3% of home value | A simplified estimate of financing cost and the opportunity cost of equity capital. |
| Total estimated unrecoverable cost | 5% per year | A screening estimate, not a universal rule. |
The video separates the cost of capital into debt and equity. Interest on borrowed money is a financing cost. Money used as a down payment also has an opportunity cost because it could otherwise be invested elsewhere. The video estimates the difference between expected stock and real-estate returns, then simplifies that difference to 3% for its example.
Examples: Compare Rent With Ownership Costs
Suppose a home is valued at ₹80,00,000. Under the simple 5% Rule for Rent vs Buy, estimated annual unrecoverable ownership costs are ₹4,00,000. Dividing by 12 gives an estimated monthly cost of about ₹33,333.
If a comparable home can be rented for ₹28,000 per month, rent is below the simplified ownership-cost estimate. If rent is ₹38,000 per month, the estimate points the other way financially. Neither result alone settles the decision: compare genuinely similar homes and check the assumptions.
| Home value | 5% annual estimate | Monthly estimate | How to interpret it |
|---|---|---|---|
| ₹40,00,000 | ₹2,00,000 | ₹16,667 | Compare with rent for a similar home. |
| ₹80,00,000 | ₹4,00,000 | ₹33,333 | Rent below this is lower than the estimate. |
| ₹1,20,00,000 | ₹6,00,000 | ₹50,000 | Use local costs before drawing a conclusion. |
Try the 5% Rule Calculator
Enter the home value and monthly rent. Adjust the annual unrecoverable-cost percentage if you want to test a different estimate. This calculator compares rent with estimated monthly ownership costs; it does not predict home prices or determine mortgage affordability.
At these assumptions, rent is below the estimated unrecoverable ownership cost.
This simplified calculator excludes transaction costs, rent increases, appreciation, tax effects and individual circumstances. Include local taxes, maintenance, financing and opportunity costs in your own analysis.
Why the Mortgage Payment Is Not the Right Comparison
A mortgage payment is made up of interest and principal. Interest is a financing cost, while principal repayment generally transfers cash into home equity. Comparing the full mortgage payment directly with rent can therefore give a distorted picture.
You still need enough cash flow to pay the full mortgage, taxes, insurance, maintenance and other bills. For broader household planning, see the 50/30/20 budget rule guide.
When Might You Use 4% Instead?
The video explains that its 5% estimate could be adjusted downward when the opportunity cost of equity is lower—for example, depending on the investor’s asset mix and tax situation. It mentions 4% as a possible rough estimate for a more conservative portfolio or a taxable investor in its original context.
Your opportunity cost depends on investment alternatives, tax treatment, risk tolerance and time horizon. You can explore assumptions with the required rate of return calculator and real return calculator.
Applying the Rule in India
The video is based on a Canadian context, so its property-tax and expected-return assumptions should not be transferred directly to India. Property taxes, maintenance, loan terms, stamp duty, registration fees, insurance, rental demand and tax treatment vary by location and property type.
Include one-time purchase costs in a longer-term comparison, and consider how long you expect to stay. If you are weighing borrowing against investing, the loan vs invest calculator can help you explore a related trade-off.
Checklist Before Deciding to Rent or Buy
- Compare rent and ownership costs for genuinely comparable homes.
- Separate mortgage interest from principal repayment when analysing unrecoverable costs.
- Estimate property taxes, maintenance and cost of capital rather than assuming 5% is exact.
- Budget for the full mortgage payment and other bills, even though principal is not treated as an unrecoverable cost in this rule.
- Include stamp duty, registration, moving, renovation and other transaction costs in a longer-term model.
- Test how the decision changes if you move sooner than expected, rent rises or repairs cost more.
- Consider non-financial priorities such as flexibility, stability, family needs and location.
Test Your Understanding: 5% Rule Quiz
Answer these five questions to check the key concepts from the video and this guide.
1. What should you compare when applying the 5% Rule?
2. Which three components add up to the video’s 5% estimate?
3. Why is the full mortgage payment not treated as an unrecoverable cost?
4. What should an Indian buyer do with the video’s 5% estimate?
5. Which statement about the 5% Rule is most accurate?
Choose one answer for each question, then check your answers.
Where Can You Continue Learning With Stock Charcha?
Explore these resources to build your financial knowledge and make more informed decisions:
For official Indian banking and financial information, consult the Reserve Bank of India. You can also watch the original video on YouTube.