Buying a car is exciting, but the real cost goes beyond the showroom price. You may need to pay a down payment, monthly loan instalments, fuel, insurance, maintenance, parking and other charges. The 20/4/10 Rule for Car Buying is a simple budgeting guideline that can help you decide whether a car is affordable before you commit.
The rule suggests making a down payment of at least 20%, financing the balance for no more than four years, and keeping total transport costs within 10% of your gross monthly income. It is a planning framework—not a lender requirement or a guarantee that a purchase is affordable. Explore the Stock Charcha calculators, learn about the other finance rules, and review your budget before taking a loan. The 20/4/10 Rule for Car Buying works best alongside a broader monthly plan, such as the 50/30/20 budget rule.
Watch the lesson above, then use the calculator to test your own assumptions.
What Is the 20/4/10 Rule for Car Buying?
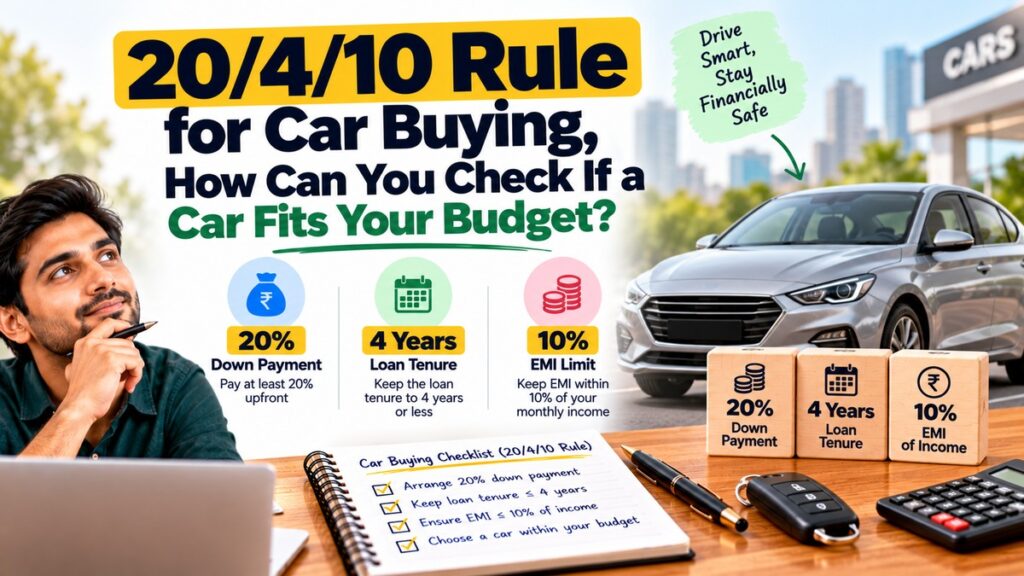
The 20/4/10 Rule for Car Buying breaks a major purchase into three checks:
- 20% down payment: Pay at least one-fifth of the car’s purchase price upfront, so you borrow less.
- 4-year loan: Aim to repay the car loan in 48 months or less. A shorter tenure generally reduces the time you remain in debt, although the EMI may be higher.
- 10% transport-cost limit: Try to keep total monthly transport expenses—not just the EMI—within 10% of gross monthly income.
The 20/4/10 Rule for Car Buying is a popular personal-finance guideline, not an official Indian financial regulation. Your actual limit should reflect your take-home pay, household responsibilities, emergency savings, existing EMIs and other goals.
How Does the 20% Down Payment Work?
To apply the 20/4/10 Rule for Car Buying, suppose a car costs ₹8 lakh on-road. A 20% down payment would be ₹1.6 lakh, leaving ₹6.4 lakh to finance before any additional fees or adjustments. A larger down payment can reduce the loan principal and may lower the EMI and total interest paid. This is one reason the 20/4/10 Rule for Car Buying emphasizes saving before shopping.
When applying the 20/4/10 Rule for Car Buying, do not empty your emergency fund just to reach the 20% mark. Keep money aside for unexpected expenses and check whether the quoted price includes registration, insurance and other charges. If you have not built a cash buffer yet, review the three-to-six-month emergency fund rule before committing savings to a car. Compare the final on-road price rather than relying only on an advertised ex-showroom price.
Why Does the Rule Suggest a Maximum Four-Year Loan?
A longer loan tenure can make the monthly EMI look smaller, but it may increase the total interest paid and keep you in debt for longer. The four-year part of the 20/4/10 Rule for Car Buying encourages you to choose a car whose repayments fit a shorter schedule.
For example, under the 20/4/10 Rule for Car Buying, a ₹6.4 lakh loan at an illustrative 9% annual interest rate for four years would have an EMI of roughly ₹15,900. The exact EMI depends on the lender’s rate, fees, repayment terms and the final loan amount. Use the available calculators and compare actual lender offers before signing.
What Counts Toward the 10% Transport Budget?
The 10% part of the 20/4/10 Rule for Car Buying is easy to misunderstand. It refers to the broader cost of using and owning the car, not only the loan instalment. Depending on your situation, include:
- Monthly car-loan EMI
- Fuel or charging expenses
- Insurance costs, averaged across the year
- Routine servicing, tyres and repairs
- Parking, tolls and other recurring transport costs
When using the 20/4/10 Rule for Car Buying, if your gross monthly income is ₹1,00,000, 10% equals ₹10,000. If the EMI alone is ₹15,900, the purchase already exceeds this guideline before fuel or maintenance. That is a signal to consider a less expensive car, a larger down payment, or delaying the purchase—not a reason to stretch the budget.
Although the 20/4/10 Rule for Car Buying uses gross income, it can be too generous for households with high taxes, rent, dependants or existing debt. For a conservative decision, also check affordability against your take-home pay and essential expenses.
Can You Estimate Your Own Car Budget?
Use this simple calculator to estimate the maximum car price implied by the 20/4/10 Rule for Car Buying. It assumes a 20% down payment and a four-year loan. The transport-cost limit is 10% of gross monthly income, and the calculator reserves a portion of that limit for running costs before estimating the EMI budget.
20/4/10 Car Affordability Calculator
Illustration only. The estimate uses an EMI budget equal to 10% of gross monthly income minus running costs, with a 48-month loan. It excludes fees and does not replace a full household budget.
When Might the 20/4/10 Rule Not Fit Your Situation?
The 20/4/10 Rule for Car Buying is a starting point, not a universal answer. It may be difficult to apply in cities where parking and commuting are expensive, or for households whose income varies from month to month. It may also be too restrictive—or too loose—depending on whether the vehicle is essential for work or whether you already have significant financial commitments.
Before applying the 20/4/10 Rule for Car Buying, check your emergency fund, health and term insurance needs, existing loan repayments and near-term goals. If a car purchase forces you to stop essential savings or rely on credit for everyday expenses, it may be unaffordable even if one part of the rule appears to fit.
A used car may reduce the amount you need to borrow, but compare its condition, service history, insurance and likely repair costs before deciding. Depreciation, resale value and maintenance differ by model and age, so the 20/4/10 Rule for Car Buying should be applied to the full expected cost of ownership—not just the sticker price.
What Should You Check Before Taking a Car Loan?
- Compare the final on-road prices from multiple dealers. A price that fits the 20/4/10 Rule for Car Buying on paper should still leave enough room for savings and irregular expenses.
- Request the lender’s annual interest rate, processing fees, total repayment amount and foreclosure terms in writing.
- Calculate the EMI and add fuel, insurance, maintenance and parking costs.
- Check the impact on your monthly budget after rent, groceries, utilities, dependants and savings.
- Avoid choosing a longer tenure only to make a more expensive car appear affordable.
For general investor and financial-awareness material, visit SEBI Investor. For borrowing, use the lender’s official documentation and compare the full cost rather than relying on a single EMI quote.
What Are the Main Takeaways?
The 20/4/10 Rule for Car Buying offers a quick three-part check: at least 20% down, a loan term of four years or less, and total transport expenses ideally within 10% of gross monthly income. Use it to question a purchase before committing, not to justify spending up to a limit.
Choose a vehicle that leaves room for emergencies, ongoing savings and other priorities. Actual loan costs depend on lender terms, while ownership costs can change over time. Revisit the 20/4/10 Rule for Car Buying if your income, household costs or driving needs change. No budgeting rule can guarantee that a car will remain affordable in every circumstance.
Disclaimer: This article is for educational purposes only and is not financial, lending or investment advice. The 20/4/10 guideline is not an official rule or a guarantee of affordability. Verify loan terms and assess your personal circumstances before borrowing.
Where Can You Continue Learning With Stock Charcha?