Before picking a retirement corpus of ₹1 crore, ₹3 crore or ₹5 crore, work backwards from the life you want to fund. The 25x Rule gives you a quick starting estimate based on annual expenses, plus a way to test how far away the goal may be.
Imagine your household spends ₹50,000 a month today. A retirement target of ₹1 crore might sound large, but whether it is enough depends on your future spending, inflation, other income and how long retirement lasts. The 25x Rule helps turn a vague “I need a few crores” goal into a first number you can inspect and refine.
It is a rule of thumb, not a promise that a particular corpus will last for life. At Stock Charcha, the useful part is making the assumptions visible: change your monthly expenses, retirement timeline and return assumption to see how the estimate changes.
What Does the 25x Rule Actually Mean?
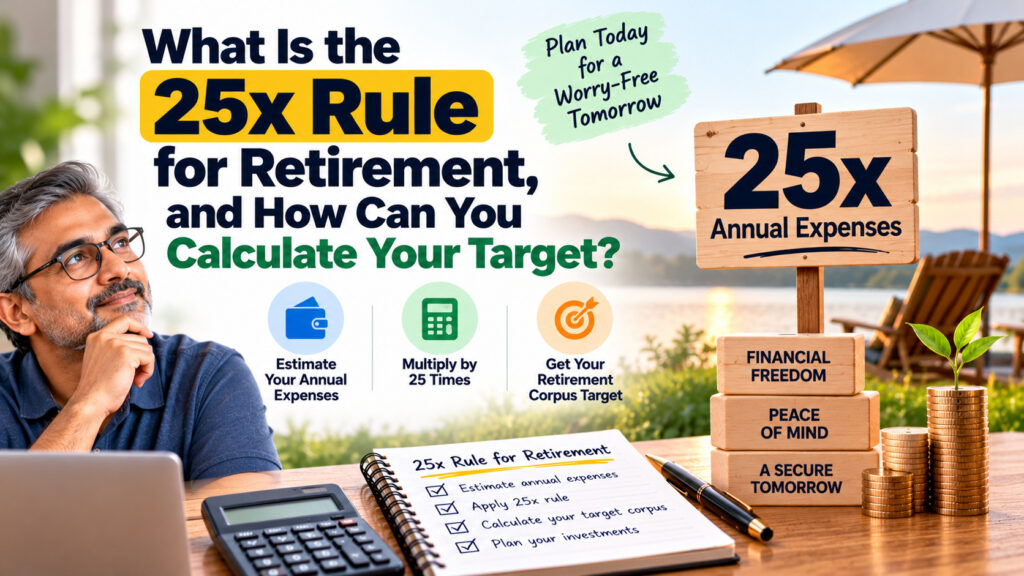
The 25x Rule says to multiply your estimated annual retirement expenses by 25 to get a rough target corpus. The idea is linked to a simple withdrawal illustration: 1 divided by 25 equals 4%, so a corpus 25 times annual expenses corresponds to withdrawing 4% of that starting amount in the first year.
For example, if you expect to spend ₹6 lakh a year in retirement, the 25x calculation gives ₹1.5 crore. This is a starting estimate in today’s expense terms; it does not automatically account for inflation between now and retirement, taxes, changing medical costs or the actual returns earned after retirement.
How Do You Calculate a 25x Retirement Target?
Start with expenses rather than choosing a round corpus number. Use the monthly amount you expect to spend on housing, food, utilities, transport, healthcare, insurance, family support, travel and other regular needs. Then annualise it and multiply by 25.
- Estimate monthly expenses: separate essentials from optional spending and include irregular costs such as annual premiums and home repairs.
- Convert to annual expenses: multiply the monthly estimate by 12.
- Apply the multiple: multiply annual expenses by 25 to get the rough corpus target.
- Adjust for the future: account for inflation, pension or other dependable income, major liabilities and the length of retirement.
The calculator first shows the 25x target based on expenses entered today, then estimates how much those expenses could rise by the retirement date using your inflation assumption. It also estimates a monthly SIP that could build the future target under the return assumption you enter. These are mathematical illustrations: actual inflation and market returns will vary, and taxes, fees and existing retirement assets are not included.
Why Does Inflation Change the 25x Rule So Much?
The same lifestyle can cost substantially more in 15 or 25 years. If today’s monthly expenses are ₹50,000 and inflation averages an assumed 6% annually for 20 years, those expenses would grow to roughly ₹1.60 lakh a month. This is an illustration, not a prediction of future inflation.
That is why a ₹1.5 crore target based on today’s ₹6 lakh annual spending should not automatically be treated as the target you need two decades from now. Review your estimate periodically, especially after changes in housing, family responsibilities, healthcare needs or retirement age. For official context on inflation and monetary policy, see the Reserve Bank of India; future inflation can still differ from past experience and assumptions.
How Much Should You Invest Each Month to Reach the Target?
Once you have a future target, a SIP calculation can help translate it into a monthly saving amount. For example, the supplied video uses a ₹1.5 crore target, a 20-year period and an assumed 12% annual return, producing an approximate SIP of around ₹16,000 a month. Treat that result as illustrative because returns are not fixed and a different compounding convention or calculator setting can change the estimate.
Use the Stock Charcha SIP Calculator to test monthly contributions and assumed returns. If you already have investments earmarked for retirement, include them in a broader plan instead of assuming every rupee of the target must come from a new SIP. A market-linked projection is not a guarantee, and a higher assumed return can make the required monthly amount look lower while also implying more uncertainty.
What Are the Limits of the 25x Rule?
The 25x Rule is easy to use because it compresses a complex retirement problem into one multiplication. But it does not by itself model your asset allocation, market sequence risk, tax treatment, healthcare shocks, longevity or how spending may change after retirement. The 4% withdrawal concept associated with the rule originated in a particular research context and should not be treated as a universal safe rate for every Indian household or every retirement period.
- Retirement length: retiring at 50 may require a different plan from retiring at 65 because the money may need to last longer.
- Other income: pension income, rental income or other dependable cash flows may affect the amount that must come from your portfolio.
- Returns and timing: poor market returns early in retirement can be more damaging when withdrawals continue.
- Expenses: healthcare, family support and lifestyle costs can rise or fall over time; a fixed estimate may miss those changes.
- Taxes and fees: the amount available to spend can be lower than the headline portfolio value suggests.
For broader investor education and risk awareness, consult SEBI’s Investor website. You can also use the Stock Charcha calculator library to explore related financial calculations, while keeping each tool’s assumptions in mind.
How Can You Make the 25x Rule More Useful for Your Situation?
Use it as the first line in a plan, not the final answer. Write down your expected retirement age, monthly expenses in today’s money, existing retirement savings, likely pension or other income and the number of years left to invest. Run conservative and optimistic scenarios rather than relying on one return figure.
Next, revisit the plan at least once a year and after major life changes. If the gap looks too large, possible levers include saving more, increasing contributions as income rises, adjusting the retirement date, reviewing expenses or checking whether the assumed lifestyle matches your priorities. Do not make a decision solely because one calculator produces a neat number.
Stock Charcha’s approach is to help you verify the arithmetic yourself and understand what it can—and cannot—tell you. Compare your retirement assumptions with your wider financial picture, including emergency savings and insurance, rather than investing every available rupee toward one long-term target.
Can You Check Your Understanding of the 25x Rule?
Try five randomly selected questions. Use “New questions” to generate another set from the quiz bank.
What Should You Do After Finding Your 25x Number?
Calculate your annual expenses, multiply by 25, then stress-test the result for inflation, retirement length and uncertain returns. The number gives you a useful starting point, but your retirement plan should evolve with your circumstances. If you need a decision tailored to your own finances, consider speaking with a qualified financial planner or SEBI-registered investment adviser.
Where Can You Continue Learning With Stock Charcha?