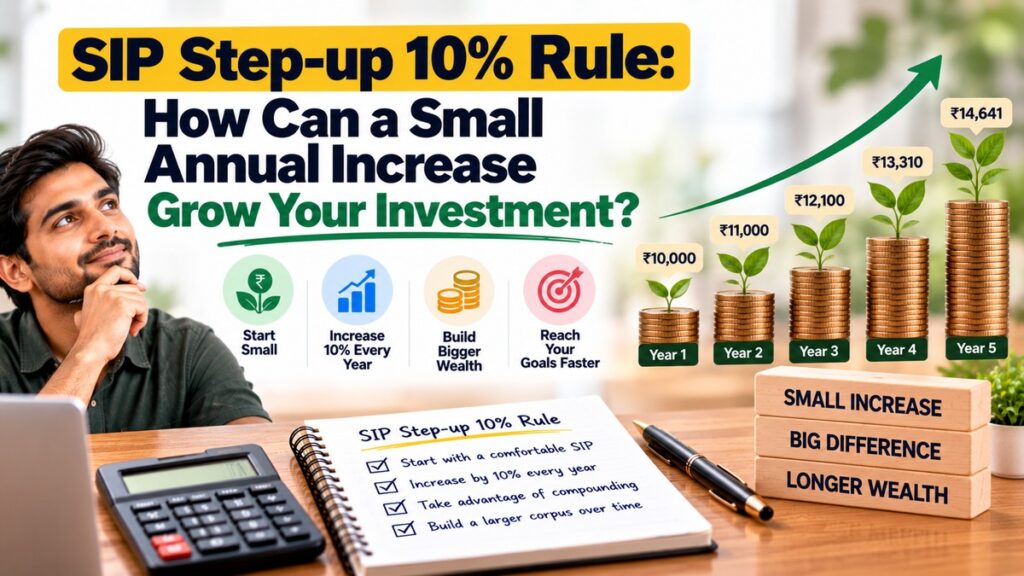
A regular SIP helps you invest consistently, but what happens when you increase that contribution as your income grows? The SIP Step-up 10% Rule is a simple habit: start with an affordable monthly SIP and aim to increase it by 10% every year. Over a long period, higher contributions may help you build a larger corpus than keeping the monthly amount unchanged.
This guide explains how a step-up SIP works, how to estimate the difference, and what to check before choosing an annual increase. You can also explore our SIP calculator, read what an SIP is, and browse other personal finance rules on Stock Charcha.
What Is the SIP Step-up 10% Rule?
The SIP Step-up 10% Rule means increasing your monthly systematic investment plan (SIP) contribution by 10% once each year. If you begin at ₹5,000 per month, a 10% step-up makes the next year’s contribution ₹5,500 per month. The following year it becomes ₹6,050, and it continues rising on the new amount rather than on the original ₹5,000.
This is an investing habit, not a regulation or a guaranteed-return formula. Some investors choose a fixed rupee increase instead—for example, adding ₹500 or ₹1,000 to the monthly SIP each year. A percentage step-up grows with the contribution; a fixed increase is easier to predict in rupee terms.
Why Can an Annual SIP Increase Make a Difference?
The main idea behind the SIP Step-up 10% Rule is to make your investment contribution grow alongside your earning capacity, rather than leaving it unchanged for the entire goal period.
There are two forces at work: you invest more money over time, and each contribution has more time to potentially grow. The SIP Step-up 10% Rule can also help align saving with salary increments, provided your income actually rises and your essential expenses remain covered.
- It can keep savings aligned with income: review the SIP when your salary or business income increases.
- It builds the habit gradually: an annual review is often easier to plan for than frequent changes.
- It may improve long-term outcomes: additional contributions can compound, but market-linked returns are uncertain.
Inflation matters too. If your income and SIP stay flat for decades, the purchasing power of the contribution may shrink. Increasing contributions can help you respond to rising costs, although it does not remove investment risk or guarantee that returns will beat inflation. Use the real return calculator to think in inflation-adjusted terms.
How Do You Calculate a 10% Step-up SIP?
When applying the SIP Step-up 10% Rule, calculate each new monthly amount from the previous year’s amount, then check whether that higher contribution still fits your monthly cash flow.
Start with a monthly amount you can maintain, then multiply it by 1.10 at each annual step-up. For example, a ₹5,000 monthly SIP becomes ₹5,500 in year two, ₹6,050 in year three and ₹6,655 in year four. The annual contribution also rises because the higher monthly amount is invested for 12 months.
The calculator below compares a flat SIP with a SIP that increases every year. It adds each monthly contribution at the end of the month and applies an assumed annual return converted to an equivalent monthly rate. Actual mutual fund returns fluctuate, and real-world results will differ because of market performance, expense ratios, taxes, timing and the exact step-up schedule.
Step-up SIP Calculator
Illustration only, not a forecast or recommendation. The calculator assumes a constant rate for mathematical illustration; actual market returns vary, may be negative, and are not guaranteed.
Is a 10% Step-up Suitable for Every Investor?
You do not need to follow the SIP Step-up 10% Rule mechanically. Treat the percentage as a planning benchmark and adjust it to your circumstances.
No. The SIP Step-up 10% Rule is a useful starting point, not a target everyone must follow. A 10% increase may be manageable for someone whose income rises steadily, but it can be unrealistic if earnings are irregular or household expenses are increasing quickly.
Before increasing your SIP, make sure you can cover essential bills, keep suitable emergency savings, and manage expensive debt. If your income is variable, consider reviewing the contribution annually and increasing it only when your budget supports it. You can revisit your spending plan with Stock Charcha’s 50:30:20 budget guide.
How Can You Set Up a Step-up SIP?
Before switching on the SIP Step-up 10% Rule, read your platform’s terms and confirm when the increased instalment will begin.
- Choose a monthly contribution that fits your current budget.
- Check whether your mutual fund platform supports an automatic annual step-up; features and terms vary.
- Choose a percentage or fixed rupee increase that is realistic for your income.
- Review the SIP at least once a year, especially after a salary change or major expense.
- Check your asset allocation and goal timeline rather than choosing a fund based only on recent returns.
Do not assume every scheme or platform uses identical settings. Confirm the step-up date, frequency, minimum or maximum limits, and how to pause or modify the instruction before confirming it. For investor education, visit SEBI Investor and AMFI’s investor knowledge centre.
What Mistakes Should You Avoid?
A common misunderstanding is that the SIP Step-up 10% Rule itself creates returns. It only changes the amount you contribute; the investment outcome depends on market performance and other costs.
- Starting too high: an ambitious SIP that repeatedly gets stopped may be less practical than a sustainable one.
- Expecting fixed returns: a calculator’s assumed return is not a promise.
- Ignoring emergencies: don’t increase long-term investments at the expense of near-term needs.
- Chasing the biggest projected corpus: choose an amount based on affordability, risk tolerance and goals.
- Forgetting inflation and taxes: the final number is not the same as future purchasing power or after-tax proceeds.
Frequently Asked Questions About the SIP Step-up 10% Rule
Does a step-up SIP automatically increase by 10% every month?
No. In the common annual step-up arrangement, the monthly contribution amount is raised once a year. Confirm the schedule selected on your platform.
Is a 10% annual step-up better than a fixed SIP?
It can lead to a larger projected corpus because you contribute more, assuming other inputs are the same. It is not automatically better for every budget, and market returns remain uncertain.
Can I step up my SIP by 5% or 15% instead?
Often, platforms offer different percentage or fixed-amount options, but availability varies. Choose a rate you can sustain rather than stretching your budget to meet a rule.
Does the SIP Step-up 10% Rule guarantee wealth creation?
No. It encourages increasing contributions, but the outcome depends on investment performance, costs, duration, contribution discipline and other factors.
Test Your Understanding
Answer five questions to check what you learned. Select “New questions” to generate another set.
Where Can You Continue Learning With Stock Charcha?
Disclaimer: This article is for educational purposes only and is not investment advice. Mutual fund investments are subject to market risks. Read scheme documents carefully and consider your goals, time horizon and risk tolerance.