Enter your monthly SIP, expected return, goal horizon and how long you might wait. This SIP delay calculator shows what the delay costs and how much more you would need to invest to catch up.
SIP Delay Calculator
Compare starting your SIP today with starting it later, for the same goal date.
Start now vs start later
| At your goal date | Start now | Start later |
|---|
Cost of different delays (same SIP, return and goal date)
| Delay | Cost of delay (₹) | SIP needed to catch up (₹) |
|---|
Illustrative estimates only. Actual returns vary with the market.
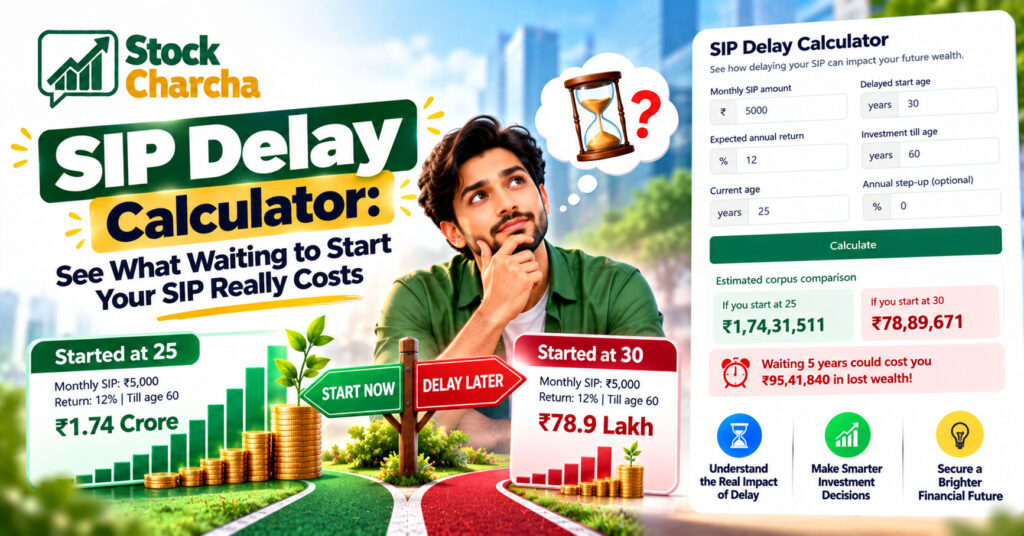
Waiting five years to start a ₹10,000 SIP does not cost you five years of instalments. At an illustrative 12% over a 20-year goal, it costs about ₹49.46 lakh of corpus. A SIP delay calculator puts a price on “I will start next year”.
How do you use this SIP delay calculator?
- Enter the monthly SIP you plan to invest.
- Add the yearly return you expect. Pick a number you can defend, not the highest one you have heard.
- Enter the years until your goal, such as retirement or a child’s education.
- Enter how long you might wait before starting. Half years such as 1.5 work too.
- Press Calculate, then read the cost of delay, the catch-up SIP and both tables. Use Copy result to save a summary.
Stock Charcha built this SIP delay calculator so both plans end on the same goal date, which is the only fair way to compare starting now with starting later.
How does the SIP delay calculator work out the cost of waiting?
Both plans finish on the same date. Starting now means investing for the full period, while the delayed plan invests only for the months left after the wait. The calculator treats each instalment as invested at the start of the month and compounds it monthly.
Corpus = P × [((1 + i)n − 1) ÷ i] × (1 + i)
Here P is your monthly SIP, i is the monthly return and n is the months invested. The cost of delay is the corpus from starting now minus the corpus from starting later. The catch-up SIP is your SIP scaled up by the ratio of the two corpuses.
What does a worked example look like?
Take a ₹10,000 SIP at an illustrative 12% with a 20-year goal, starting now or after a 5-year wait.
| At the goal date | Start now | Start after 5 years |
|---|---|---|
| Investing period | 20 years | 15 years |
| Total invested | ₹24,00,000 | ₹18,00,000 |
| Estimated corpus | ₹99,91,479 | ₹50,45,760 |
| Estimated returns | ₹75,91,479 | ₹32,45,760 |
The delayed plan ends with about ₹49.46 lakh less. These figures are illustrative, not a promise, and real returns change every year.
Why is the loss bigger than the money you skipped?
By waiting five years you skip ₹6,00,000 of instalments, yet you lose about ₹49.46 lakh of corpus. The gap exists because the early instalments would have had the most time to compound.
Early money does the heaviest lifting. That is why the SIP delay calculator shows a loss many times larger than the amount you did not invest. Stock Charcha’s other SIP calculators show the same pattern: the earliest years matter most.
How does the cost grow with each year of delay?
Here is the same SIP, return and 20-year goal with different waiting periods.
| Delay | Cost of delay | SIP needed to catch up |
|---|---|---|
| 1 year | ₹12.38 lakh | ₹11,415 |
| 2 years | ₹23.37 lakh | ₹13,053 |
| 5 years | ₹49.46 lakh | ₹19,802 |
| 10 years | ₹76.68 lakh | ₹43,004 |
The cost keeps rising with every year, and the catch-up SIP rises even faster. A one-year delay already costs about ₹12.38 lakh, and a 10-year delay needs roughly ₹43,004 a month, more than four times the original SIP.
How much more must you invest to catch up?
After a 5-year delay in the main example, you would need about ₹19,802 a month instead of ₹10,000 to reach the same corpus. That is roughly ₹9,802 more every month.
If that is too much, start with what you can afford now and raise it every year. You can test that with our step-up SIP calculator.
What does this SIP delay calculator leave out?
It does not deduct the fund’s expense ratio, so enter a net return for a safer result. It also ignores capital gains tax and inflation, and real SIPs do not grow in a straight line. Check current tax rules on the Income Tax Department website as of today.
The calculator is not a reason to invest money you may need soon. Build an emergency fund first, and use AMFI for fund data. Mutual fund investments are subject to market risks. Read all scheme related documents carefully before investing. At Stock Charcha we would rather show a cautious number than a flattering one.
Where should you go after using the SIP delay calculator?
New to SIPs? Start with what is SIP in mutual funds, or see how to start investing with ₹500. To size a SIP for a specific target, try our goal-based SIP calculator.
The best time to start is usually the next instalment date, so run the SIP delay calculator once more with your real numbers and then act on the result.
Founder of Stock Charcha. Stock market enthusiast, actively investing since November 2022. About the author
Educational content only. This page is not personalised financial advice. Please do your own research or speak to a SEBI-registered adviser before investing, and read our disclaimer.
Frequently asked questions
Is it ever too late to start a SIP?
No, but a later start needs a bigger SIP or a longer horizon to reach the same goal. Begin with what you can afford now, then raise the amount every year as your income grows.
Is it better to start small now or wait to invest more later?
Starting small usually wins, because early instalments compound for the longest time. Test both in the SIP delay calculator: enter the small SIP with no delay, then the larger SIP with a delay, and compare the corpus.
Does a one-year delay really matter?
It does. In the example on this page, waiting just one year costs about ₹12.38 lakh of corpus on a ₹10,000 SIP over 20 years. The longer your horizon, the more that first year is worth.
What return should I enter in the calculator?
Many planners use 10% to 12% for long-term equity projections, and a lower figure such as 8% to 10% is a safer way to plan. Enter a return net of the fund’s expense ratio for a more realistic result.
Does the SIP delay calculator include inflation or tax?
No. The corpus is shown in future rupees, so its buying power will be lower than it looks. Capital gains tax is also left out, so check current rules before you rely on the figures.